Market Trends • May 24, 2021

May Market Update – Matthew Gardner Report

By: Matthew Gardner

This video is the latest in our Monday with Matthew series with Windermere Chief Economist Matthew Gardner. In this month’s special episode, Matthew takes a deep dive into the data that helped him shape his Op-Ed piece for Inman News.

Hello there! I’m Windermere Real Estate’s Chief Economist, Matthew Gardner, and welcome to a rather special episode of Mondays with Matthew.

Why special? Well, regular viewers of my videos will know that I generally take this opportunity to give you an update on the housing related numbers that came out in the month, but this time we are going to go in a different direction.

A few weeks ago, I was asked by the real estate publication, Inman, to pen an op-ed that would offer a counterpoint to this one which they had just published.

Well, I think that many of you will agree that it’s a pretty direct position and – judging by the comments I read following its publication – was certainly one where readers were very firmly on one side of the fence or the other!

Those of you that know me at all will probably have already figured out my position on this. I went ahead and crafted my response and I do take a different view on the matter!

As I am sure that some of you don’t have access to Inman’s website, I thought it might be interesting to share with you the reasoning behind my belief that we are not about to enter a period of declining home values; but even if you are an Inman subscriber and did read the piece, I hope that you will still find this video worth watching as I will also be sharing some of the background data with you that was not included in the article, as well as to give some more context on the subject.


Home Prices Out-Pace Wages

But to start with, I must acknowledge the fact that home prices have been rising at a significantly faster pace than wages for several years now and that may well be part of the reason why some people in the industry – and some perspective home buyers – are getting concerned.
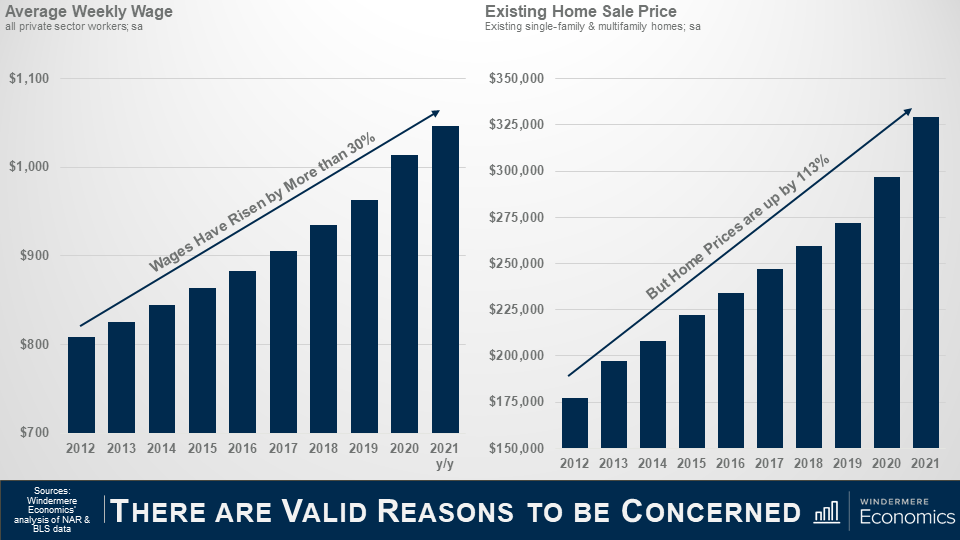
Two bar graphs side by side. On the left is the Average Weekly Wage between 2012 and 2021. Each year the bar grows, and a trendline above the bars includes text that reads: “Wages Have Risen by More than 30%. On the Right is the existing home sale price per year from 2012 to 2021. Each year the bar grows a little more and a trend line above reads “But Home Prices are up by 113%” The data sources are Windermere Economic’s analysis of N.A.R. and B.L.S.


As you can see here, since 2012, average weekly wages have risen by a little more than 30%, with the average annual gain of around 2.3% which is actually not that bad. Wages also rose by over 6% last year, which sounds great, but in reality, it was because of the pandemic.  You see, most of the job losses were in low-wage sectors which skewed the data upward – but I digress.

Anyway, during the same time period, you will see that even as wages rose, home prices have taken off and wage growth has simply not kept pace.

I often think about a quote from the Spanish philosopher and novelist, George Santayana, “Those who cannot remember the past are condemned to repeat it” which I think just about says it all!


Timeline

So, what we are going to do today is to take a look back and run through a brief timeline of events that led to the 2007 crash, and then look at where we are today and how it is totally different which leads me to speculate that there is no real reason why we should expect to see a widespread, systematic decline in home prices in the foreseeable future.
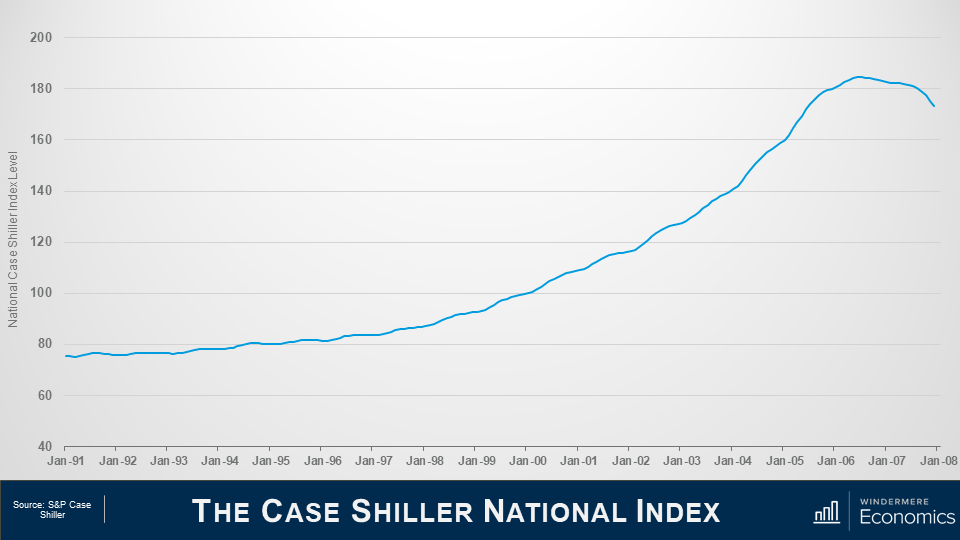
 

Line graph titled “The Case Shiller National Index” the line steadily increases a little bit between January 1991 and January 1999, but starts to increase more in the 2000’s, peaking in January 2006 and is starting to decline in January 2007 and 2008.The Source is the S&P Case Shiller.


This first chart shows the Case Shiller National Home Price Index level over time and we’ll be using it as a base for this part of the discussion.

If you are not familiar with Case Shiller, its what’s known as a repeat sales index – which means that it looks at the change in sale prices between when a home was purchased and when it was sold and is a great way to look at changes in home prices.
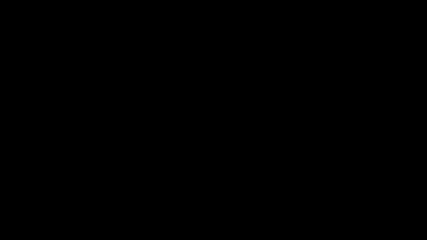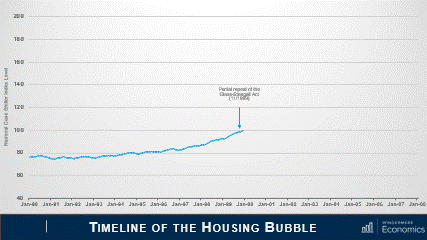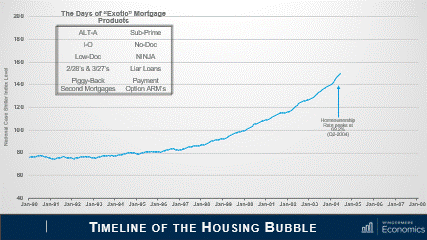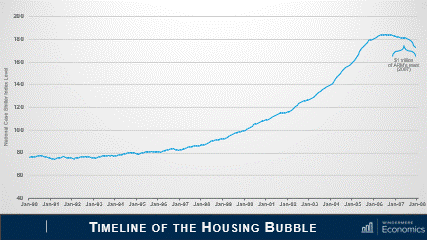
GIF of Case Shiller Index Timeline of the Housing Market from 1990 to 2008


Let’s start all the way back to the early 1990’s.

1992

In ’92, Congress enacted Title 13 of the Housing and Community Development Act and they did this to give low- and moderate-income borrowers better access to mortgage credit via loans supported by Fannie Mae and Freddie Mac.

1995

And in ‘95, President Clinton introduced a National Homeownership Strategy which had a very aggressive goal of raising homeownership levels from 65.1% to 67.5% by the year 2000 – that would be a rate of ownership in America that had never been seen before.

But this could only realistically happen if Fannie & Freddie significantly increased the share of mortgage funds going to lower income households. The Housing and Community Development Act required them to dedicate 30% of their portfolio to lower income borrowers – but the Clinton plan meant that they had to raise that share to 42%.

And it started out rather well with almost 2.8 million new homeowners created between 1993 and 1995 – and that was double that seen during the prior two years.

And because of the increase in demand that would come from greater loan volume, Fannie and Freddie moved to an automated underwriting process to speed up loan approvals. Interestingly, this then became an industry norm – but in going to an automated model, all they really did was to significantly relax the underwriting approval process.

1999

Now moving on to the very end of the decade, in November of 1999, Congress passed, and President Clinton signed, the Gramm-Leach-Bliley Act which, amongst other things, lifted most of the restrictions that prohibited any one institution from acting as any combination of an investment bank, a commercial bank, and an insurance company that were prohibited by way of the Banking Act of 1933 – otherwise known as the Glass-Steagall Act.

Now this is important as – in essence – banks could now underwrite and sell banking, securities, and insurance products and services which included, guess what, mortgage products.

2000

In 2000, the dot-com bubble burst. Something those of us here in Seattle remember all too well – and one of the major consequences of this was that investors moved away from the equity markets and, instead, turned their attention to the real estate market.

2001

By the start of 2001, the country was heading into a recession, and even though unemployment remained close to a 30-year low, the Federal Reserve wanted to stimulate borrowing and spending, so they started to lower short-term interest rates very aggressively.

2003

As you can see, over the next 3-years the market jumped with home prices rising by 7% in 2002 and 7.5% in 2003 as more would be home buyers found easier access to mortgage credit not just from Fannie or Freddie – but all of the other institutions that could now get into the game following the passing of the Gramm Leach Bliley Act.

And because of its success, the push to expand homeownership that had started under President Clinton continued under President Bush, and he introduced a “Zero Down Payment Initiative” that allowed – under certain circumstances – removal of the 3% down payment rule for first-time home buyers using FHA-insured mortgages.

2004

Well, the Bush and Clinton administrations saw their housing goals achieved with the homeownership rate increased steadily, peaking at 69.2% of households in 2004.

Ownership rates and rapidly rising home prices were driven by one thing.

Home buyers were consuming – with relish I might add – rare mortgage products with strange-sounding names such as Alt-A, sub-prime, I-O – as in interest-only -, low-doc, no-doc, or the classic NINJA loans, NINJA being an anacronym for “no income, no job, no assets”. There were also 2–28 and 3–27 loans; liar loans; piggyback second mortgages; payment-option and even “pick-a-pay date” adjustable-rate mortgages.

What could possibly go wrong!

2005

And by 2005, sub-prime mortgages had risen from 8% of total loans made in 2003 to 20%, with about 70% of sub-prime borrowers using the hybrid 2/28 and 3/27 ARMs I just mentioned, and these were mortgages with low “teaser” rates for the first two or three years, and then they adjusted periodically.

And when you add in Alt-A mortgages, the total share of just these two mortgage products rose from 10.4% in 2003 to 39.4% in 2005.

Many people chose their financing poorly. Some clearly wanted to live beyond their means and, by mid-2005, nearly 25% of all borrowers across the country were taking out interest only home loans which gave them a lower  monthly payment, as they weren’t worried about paying down the principal because home prices were going to continue to skyrocket forever – right!!?

2006

By the end of 2006, a full 90% of all sub-prime mortgages were ARM’s and with a doubling of the sub-prime share, about $2.4 trillion of new sub-prime and non-prime mortgages were used to buy homes.

2007

Well, in 2007 over $1 trillion worth of ARM’s were about to reset, and this is what really took the market down.

Why? Well, back in July of 2004, the Fed started to raise interest rates, and with all the ARM’s starting to reset, a massive number of homeowners just couldn’t afford their new payments and they started to default in droves.

2010

The ultimate outcome was that in 2010 over 2.2% of all homes in America were foreclosed on – that almost 2.9 million homes – in just one year.


So what makes it different this time around?

That’s the history lesson, so let’s compare and contrast where we are today with what happened back then.
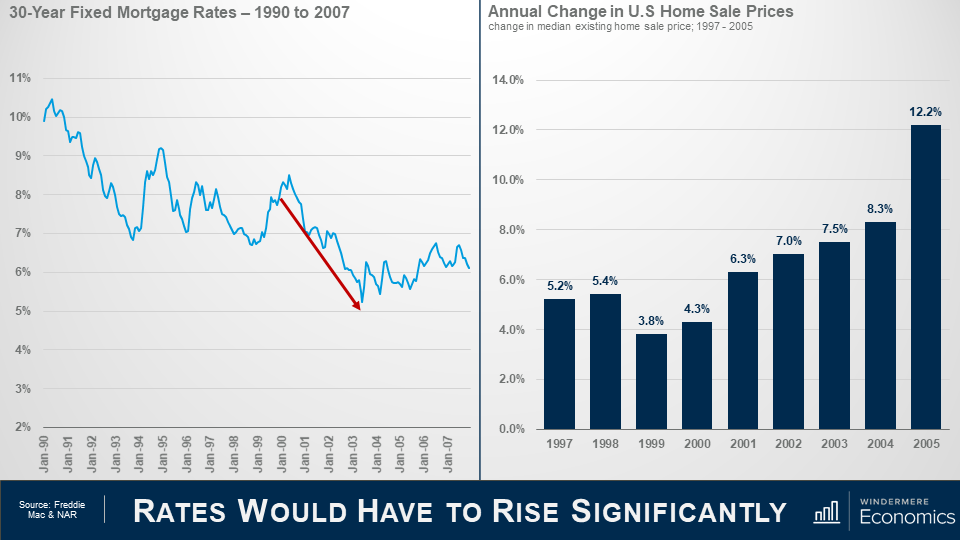
Two graphs side by side, titled together “Rate would have to rise significantly” the graph on the left is a line graph showing the 30-yearmortgage rates from 1990 to 2007. From 2000 to 2004, there’s a red arrow that highlight the decline in the number of mortgages. On the right is a bar graph that shows the annual change in U.S. Home sale prices changed in median existing home sale price from 1997-2005. There’s a steady increase from 1999 to 2004, and in 2005 there’s a share increase to 12.2% from 8.3% in 2004. The sources are Freddie Mac and NAR.


As we discussed earlier, the Fed started to lower interest rates following the dot-com bust and that flowed down to the mortgage market and rates also started to drop but it wasn’t just the Fed – investors did what they usually do during periods of economic uncertainty – they moved a lot of money into bonds, and this has a far more direct effect on mortgage rates.

By 2004, mortgage rates had dropped to a record low.

And as rates dropped, look what happened to prices – they started rising as buyer purchasing power rose, but that’s far from the only reason why home prices rose so significantly, but we will get to that later.
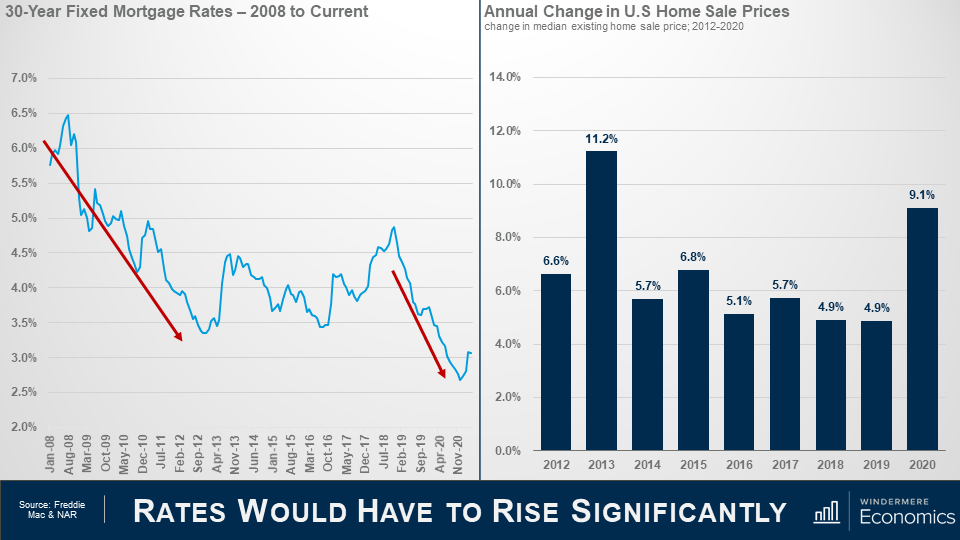
 

Two graphs side by side with the title at the bottom Rates would have to rise significantly. On the left is a line graph that shows the 30-year fixed mortgage rates from 2008 to now. There are two red arrows highlighting decreases, one from 2008 to 2021 that drops from above 6% to between 3%and 3.5%. The other red arrow highlights July 2018 to November 2020 that falls from 5% to just above 2.5%. On the right is a bar graph showing the annual change in U.S. home sale prices change in median existing home sale price from 2012-2020. Most of the graph sits below 8% except 2013 which is at 11.2% and 2020 is at 9.1%.


So, moving forward in time, you can see that rates dropped again as the financial crisis was taking hold and the country was entering a recession and rates dropped even more staring in 2019 as the Fed became concerned about inflation, slowing global growth, and trade wars.

And they offered further supported to the housing market at the onset of the pandemic by aggressively buy bonds which effectively lowered mortgage rates even further.

So far, you may be thinking, “well, its clearly the same as last time”, but I’m afraid that you’d be wrong.

You see, although sale prices surged in 2013 – realistically because home prices over corrected on the downside following the bubble – average annual price growth since 2013 has been slower we saw pre-bubble.

The median sale price rose by an average annual rate of 7.6% between 2000 and 2005, but between 2014 and 2020, the pace of appreciation was a full 1.5 percentage points lower.
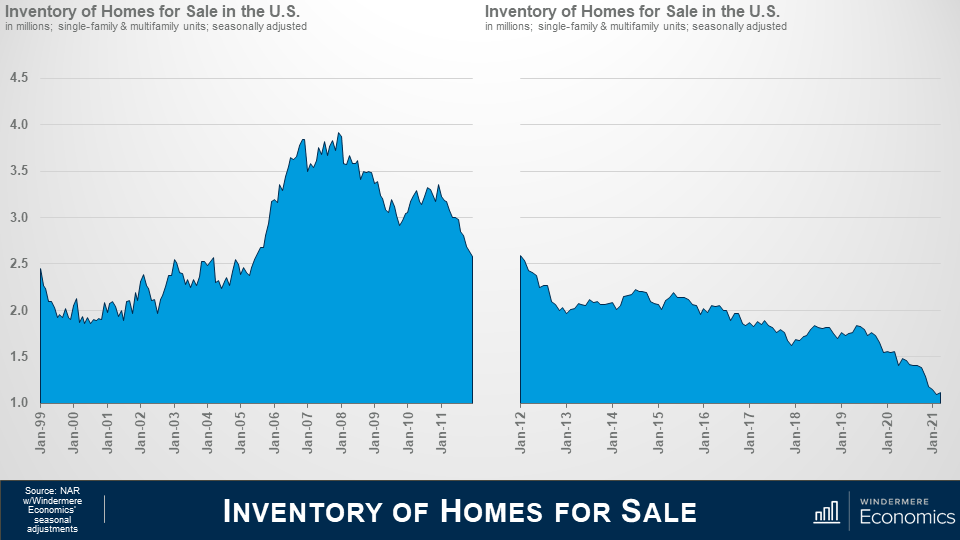
 

Two area graphs side by side with the title underneath that says inventory of homes for sale. On the left the chart shows the inventory of homes for sale in the U.S in millions; single-family & multifamily units; seasonally adjusted. There’s a sharp increase from 2005 to 2007, then a decrease after that but the graph never goes back down to pre-2005 numbers. On the right the area graph shows the inventory of homes for sale in the US in millions from 2012 to 2021. The graph shows a slow decrease over time, with sharp changes between 2012 and 2013 and again from 20119 to 2021.


I am going to talk more about mortgages shortly, but it’s important to touch on another significant difference between the 2000’s and now and that’s housing supply.

As you can see here, starting in 2001, inventory levels rose and peaked just as the bubble was about to burst. Why? Well, do you remember me telling you about the surge in unique mortgage products – specifically ARM’s?

1 in 10 borrowers in ‘05 and ‘06 took out “option ARM” loans and one-third of ARMs originated between 2004 and 2006 had “teaser” rates below 4%. Therefore, we started to see people try to sell before the rate reset and this led to the growth in listings. But how does that compare to what we’ve seen over the past several years?

The number of homes for sale has been sliding since the spring of 2011 and is currently at the lowest levels since data on total US listings started to be gathered back in 1999. Ultimately, the basic economic laws of supply and demand are working today. Prices rise on scarcity of product and lower cost of financing. Both of which we see here.
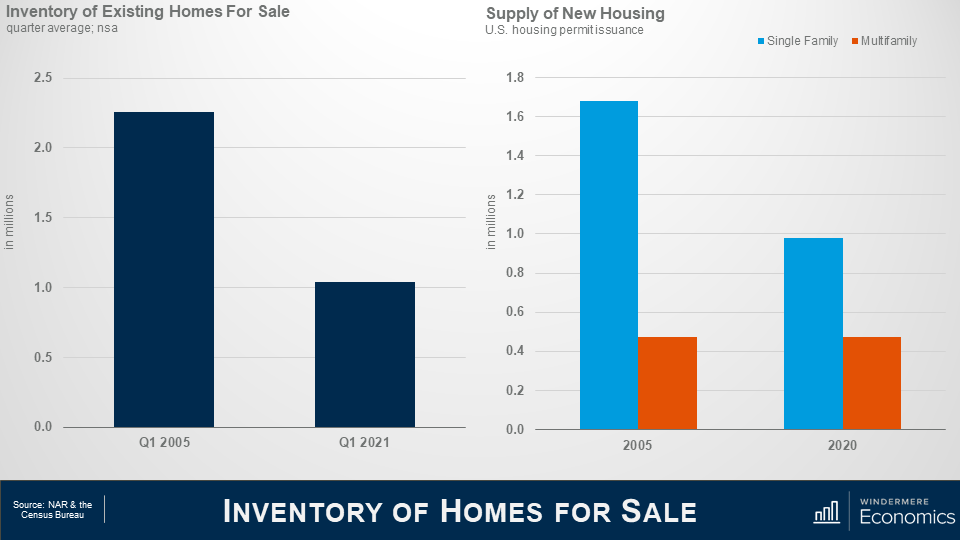
 

Two bar graphs next to each other with the title of the slide reading at the bottom inventory of homes for sale. On the left is the inventory of existing homes for sale quarter average comparing Q1 2005 and Q1 2021. The bar for Q1 2005 rises to between 2 and 2.5 million. The bar for Q1 2021 sits just above 1 million. On the right is a bar graph that shows the supply of new housing in millions for US housing permit issuances. The blue bars represent single-family permit and orang represents multi-family. In 2005 the blue bar for single-family homes sits at just above 1.6 million and the orang bar for multi-family sits between .4 and .6 million. In 2020, blue bar is almost half the blue bar in 2005, sitting at just under 1 million, and the orange bar sits around the same between .4 and .6 million.


This shows the average number of existing homes that were for sale in the spring of 2005 – a date I chose as it was before the mortgage ARMS’s started to reset – and this spring.

Clearly a significant disparity. Now some of you may say that its lower because of the pandemic, but even if I were to use the spring of 2020 as a comparison – before the pandemic took hold – listings would still be 36% lower than in 2005.

But new demand can be met by building more new homes. Almost 1.7 million single family permits were issued in 2005 when the market was booming, but fewer than 1 million single family permits were issued last year.

The multifamily side is a little more complex as we cannot distinguish between condominiums and apartments, but I would suggest that although the number is pretty close to identical, the difference is that new multifamily permits last year were focused on the apartment world, whereas they were mainly condominiums back in 2005.

With low levels of existing and new homes for sale today, prices have risen significantly, but the difference I see is that during the pre-bubble years prices were climbing more as a function of speculation rather than real demand as there were significantly more homes available back then.
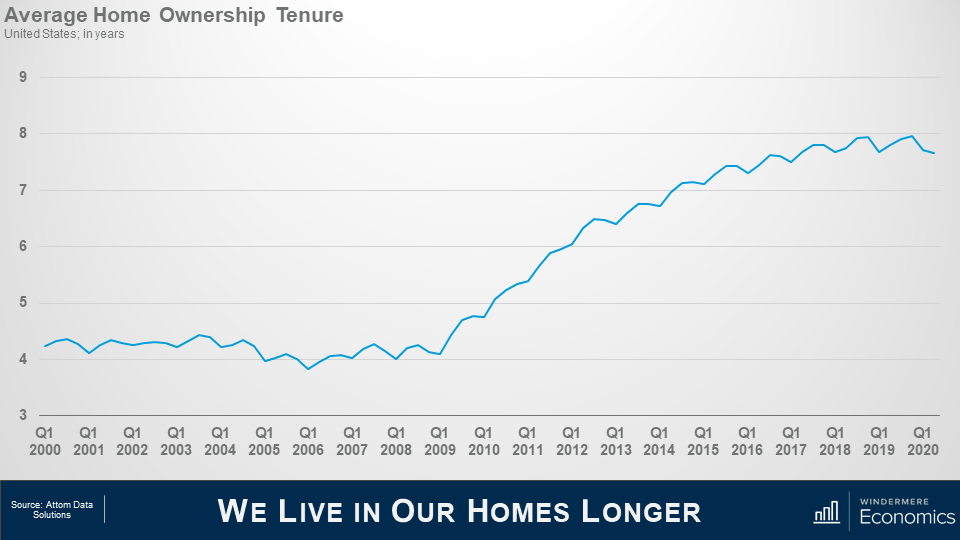
 

Line graph that shows the average home ownership tenure in the united states. A sharp increase between 2009 and 2014 shows that people are living in their homes almost double as long as they were in the early 2000’s. The source of the data is Attom Data Solutions.


And another reason why housing supply has been so weak is that we simply aren’t moving as often as we used to.

Speculation drove home buyers to move on average every 4 or so years in the early to mid 2000’s; but look at more recent years. Mobility has dropped and we now live in our homes for twice as long as we used to and this limits housing turnover which, with the relatively low levels of new construction we just discussed, also puts upward pricing pressure on housing as supply levels stay low.
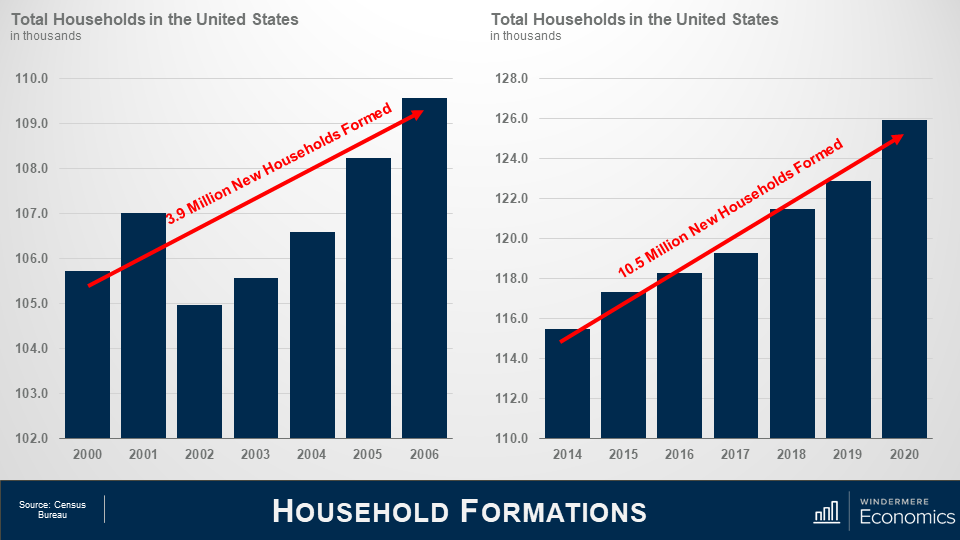
 

Two bar graphs next to each other, the slide title is household formations. On the left is a bar graph titled Total Households in the United States in thousands. The graph shows data from 2000 to 2006 and has a red trend line showing the increase of the bars. The line has text that says 3.9 million new households formed. On the right is another bar graph showing the total households in the united stats from 2014 to 2020. The red trend lines shows that 10.5 million new households were formed in that period. Data source is the Census Bureau.


On the demand side of the equation, Census data shows that 3.8 million new households were formed in the United States between 2000 2006 which is a decent enough number.

But between 2014 and 2020, we added 10.5 million new households.

Now of course not all newly formed households become home buyers. I totally understand that. But we know that the long-term average homeownership rates in America is around 65% so it’s easy to extrapolate the numbers and conclude that demand for ownership housing continues to far exceed supply.
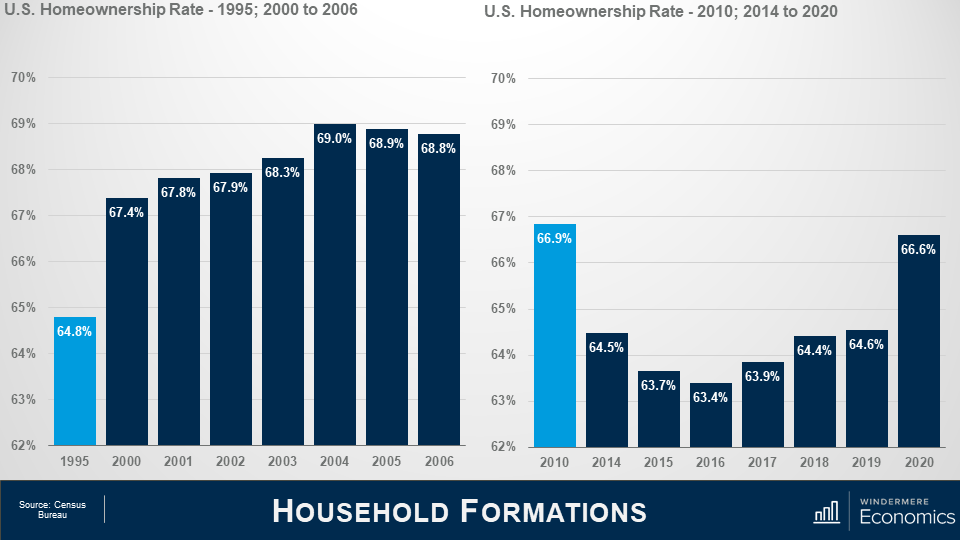
 

Two bar graphs next to each other, the title of the slide is household formations. On the left is a bar graph that shows the U.S. homeownership rate in 1995, and 2000 to 2006. 1995 is highlighted in light blue, and the bar graph represents 64.8% whereas the other bars are all above 67%, with a top number in 2014 at 69%. On the right is a bar graph that shows the US homeownership rate in 2010 and from 2014 to 2020. 2010 is highlighted with a light blue bar that shows 66.9% whereas the rest of the bars trend under 65% expect for 2020 which has a sharp increase from 2019 at 66.6%. Data source is the Census Bureau.


And talking about the ownership rate, some think that it is rising too fast – and that is proof that a speculative bubble is in place but look at this.

The pre-bubble period saw the ownership rate start to skyrocket, ultimately hitting an all-time high in 2004.

The rate was still elevated in 2010 and did not reach a bottom until 2016, but even though it has risen since, it remains well below the level seen in ’04.

Oh! If you are wondering about the 2020 spike, well I would take that with a pinch of salt. I say this as the Census Bureau survey in the first two quarters of last year were significantly affected by COVID-19 and I believe that the ownership rate was overestimated.

In fact, data for the first quarter of this year shows the ownership rate at 65.6% which is more realistic.

So, I think this clearly shows that although we continue to add households, we have not seen a speculatively driven spike in the ownership rate similar to the one we saw as the bubble was forming.

Well so far, we’ve looked at the supply of homes and how that has impacted the increase in housing prices; how demand continues to rise as more new households are formed; and we also covered the impact mortgage rates has had on home prices.


The Financing Side of the Equation

I promised you earlier that we would be returning to the financing side of the equation, because it is clear to me that it was the chief culprit behind the housing bubble.
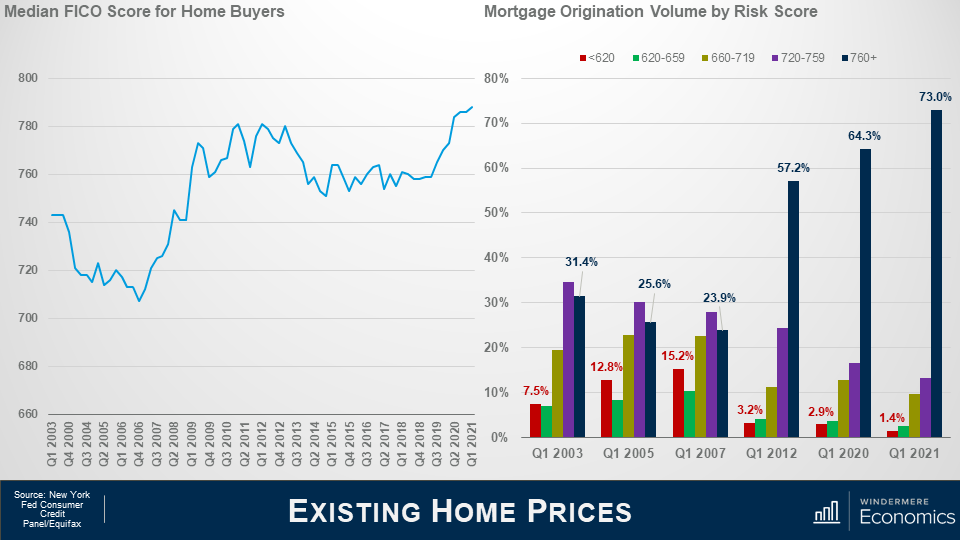
Two graphs next to each other, the slide is titled Existing Home Prices. On the left is a line graph titled Media FICO Score for Home Buyer. There’s a significant drop in credit quality in the early to mid 2000’s. On the right is a column graph titled Mortgage Origination Volume by Risk Score. Red shows less than 620, green shows between 620 and 659, green is between 660-719, purple is between 720 and 759, and navy is 760+. Those with less than 620 were borrowing 15% of all funds used to buy homes, while prime borrowers were just below 24%. Today is a much different picture with those with less than 620 scores only make up 1.4% while those with more than 760 make up 73%.


This chart shows the median credit – or FICO score – for home buyers approved for a loan and you can see the significant drop in credit quality that occurred in the early to mid-200’s.

But look at where we are today. The median credit score is now 788, and when we look at the numbers in a little more detail it’s even more remarkable as by early 2007 the riskiest borrowers – those with credit ratings below 620 – were borrowing 15% of all funds used to buy homes while prime borrowers we’re just below 24%.

But, again, look where we are today. The sub-prime share of mortgage borrowing has shrunk to just 1.4% while prime borrowers are now at a very solid 73%.

The bottom line is that credit quality is remarkably high, and not at all like the pre-bubble period.
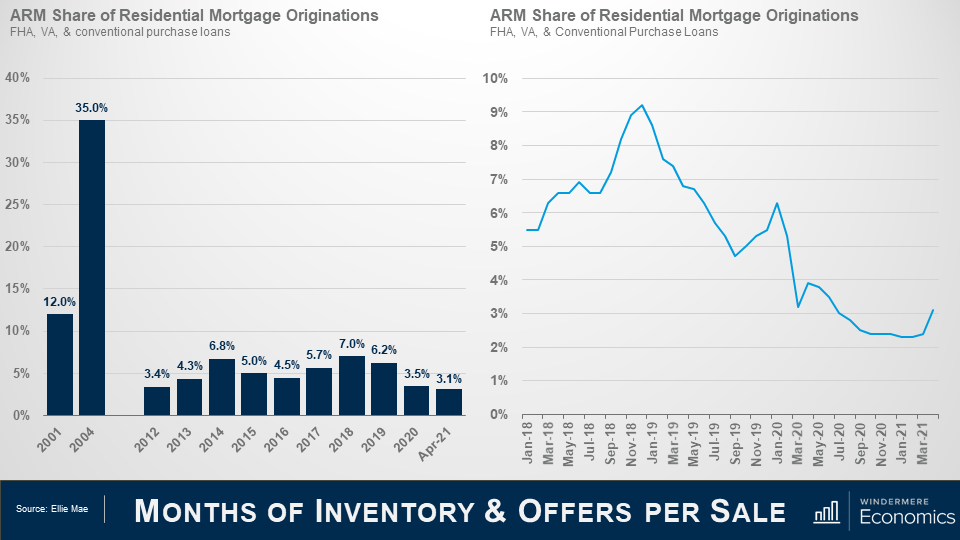
 

Two graphs next to each other, the slide is titled Months of Inventory & Offers Per Sale. On the left is a bar graph titled ARM Share of Residential Mortgage Originations. The graph shows a jump of 12% to 35% between the years 2001 and 2004, while since 2012 up until April 2021 the numbers have hovered between 3% and 7%, most recently hitting 3.1% in April 2021. On the right is a line graph titled ARM Share of Residential Mortgage Originations, showing an overall downward trend from January 2018 through March 2021, the percentage peaking in November 2018 at just above 9%. Both graphs use data for FHA, VA, and Conventional Purchase Loans.


Earlier we discussed that between 2001 and 2007, mortgage debt doubled and much of this growth came via risky mortgage products – many of which were adjustable-rate mortgages that offered the buyer significantly lower monthly payments.

ARM’s accounted for 35% of all mortgage borrowing in 2004 but the current share is far lower, which should quell any concerns that there might be a wave of ARM’s resetting that could impact the market.

And as you can see here, the share has dropped precipitously, but has levelled off over the past few months before rising modestly in March.
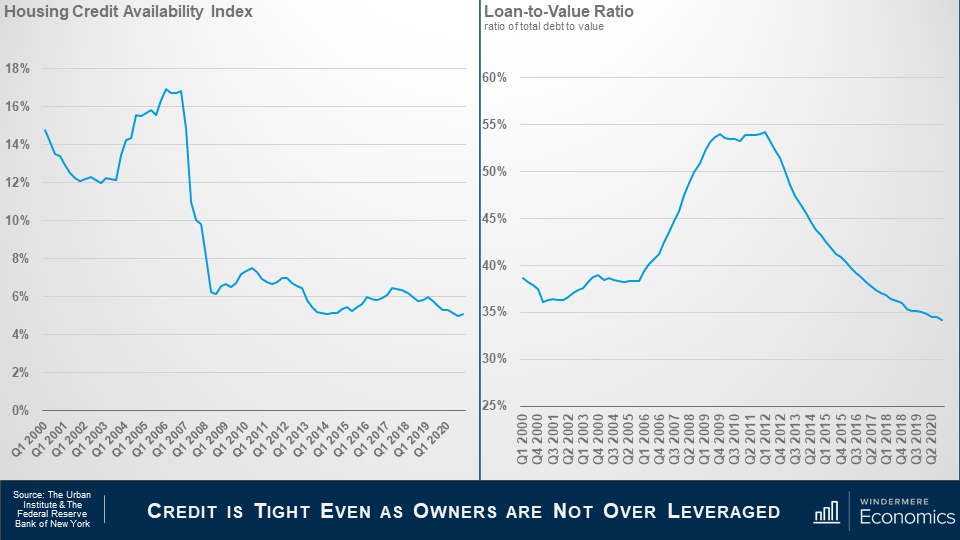
 

Two graphs next to each other, the slide is titled Credit Is Tight Even As Owners Are Not Over Leveraged. On the left is a line graph titled Housing Credit Availability Index. It shows an overall downward trend from Q1 2000 to Q1 2020, with a spike between Q1 2004 and Q1 2007. One the right is a line graph titled Loan-to-Value Ratio, which is the ratio of total debt to value. It shows data from Q1 2000 to Q2 2020. The percentage began at roughly 40% in Q1 2020, peaking at around 55% between Q4 2009 and Q4 2012 before declining steadily, coming in at just below 35% in Q2 2020.


This is data from the Urban Institute that I use regularly. It’s their Housing Credit Availability Index (HCAI) and it calculates the percentage of owner-occupied home purchase loans that are likely to default—that is, go unpaid for more than 90 days past their due date, and I like this as their methodology also weights for the likelihood of economic downturns as well.

A lower HCAI indicates that lenders are unwilling to tolerate defaults and are imposing tighter lending standards, therefore making it harder to get a loan while a higher percentage suggests that lenders are willing to tolerate defaults and are taking more risks by making it easier to get a loan.

Lenders were all good taking risks in the bubble days but are certainly looking at things very differently now.

The bottom line is that even if the current default risk doubled, it would still be well within the pre-crisis standard of 12.5% that was seen between 2001 and 2003.

And this chart shows loan to value ratios – as the bubble was forming the ratio went up as buyers were getting over leveraged but look where it is now.  Well below pre-bubble levels.

Again, tight credit and significant equity puts us in a very different place than we were in the 2000’s.


My Forbearance Forecast
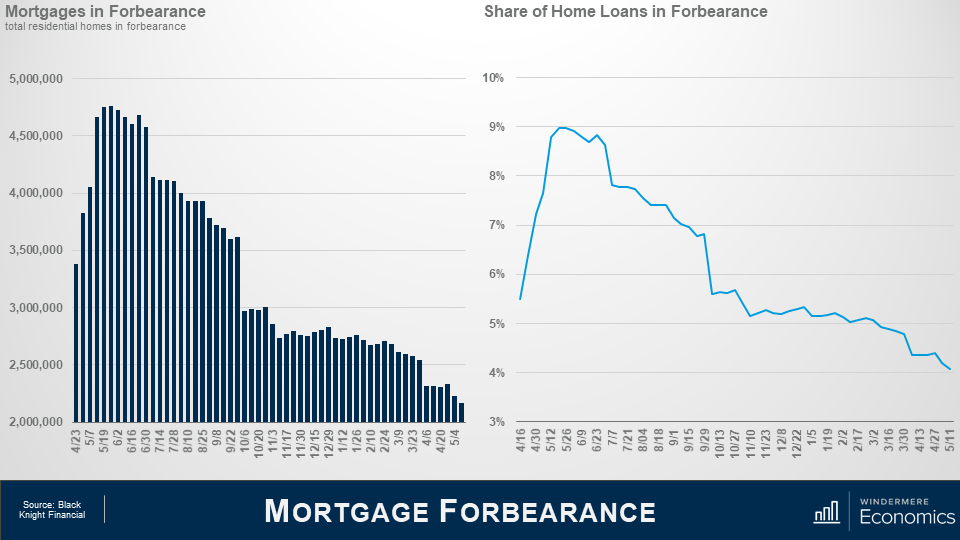
Two graphs next to each other, the slide is titled Mortgage Forbearance. On the left is a bar graph titled Mortgages in Forbearance, representing the total residential homes in forbearance. The numbers between April 23 of 2020 and May 4 of 2021 show a peak of over 4.5 million homes in May 2020, settling to just above 2 million in May 2021. On the right is a line graph titled Share of Home Loans in Forbearance, showing data for the same time period as the graph on the left. It shows a peak of around 9% in May/early June 2020, settling to around 4% in May 2021.


I am sharing forbearance data for one reason and it’s because some brokers have told me that they have clients who are thinking about waiting to buy as they believe that homes in forbearance will end up in foreclosure and the growth in supply could lead home prices to drop across the board, or at the very least allow them to pick up a home on the cheap.

But as you can see, the number of homes currently in the program is down by over half from its May 2020 peak – and that equates to 2.6 million homes.

In fact, even if all the homes still in the program did actually end up in foreclosure, it would still only represent a fraction of the nearly 10 million homes that were foreclosed on due to the housing bubble bursting.

And when we look at the share of total homes in forbearance, it peaked at just over 9% but is now knocking in the door of 4% and with over 250,000 more homes about to hit the end of their forbearance period, I anticipate that the numbers will drop further later month.

So why am I not worried that a large share of these homes will be foreclosed on? This is why.
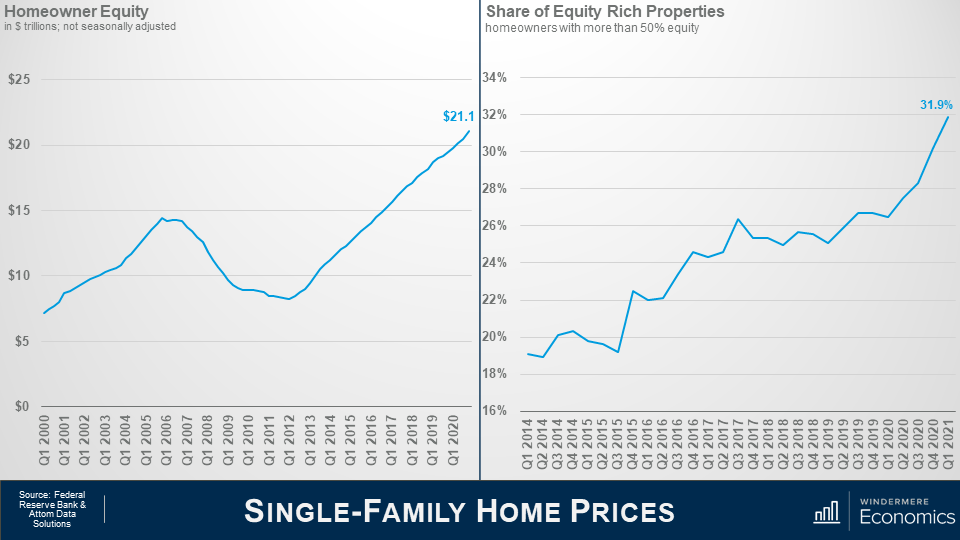
 

Two graphs next to each other, the slide is titled Single-Family Home Prices. On the left is a line graph titled Homeowner Equity, showing the dollar amount in trillions, not seasonally adjusted. Between Q1 2000 and Q1 2020, the amount rose from just over $5 trillion in Q1 2000 to $21.1 trillion in Q1 2020. One the right is a line graph titled Share of Equity Rich Properties, showing the percentage of homeowners with more than 50% equity. Between Q1 2014 and Q1 2021, the percentage rose from just below 20% in Q1 2014 to 31.9% in Q1 2021.


In the first quarter of this year homeowners were sat on over $21 trillion in equity – a truly massive figure.

You can see the buildup of equity as the housing bubble was forming and then it contracted through the housing crisis; however, since 2012 home equity levels have more than doubled.

My friends over at Attom Data Solutions estimate that, in the first quarter of this year, almost one in three homeowners in America had more than 50% equity in their homes – that’s almost 18 million homeowners.

And this tells me that a lot of owners in forbearance who just cannot get back on the right path still have the option to sell their homes in order to keep the equity that they have – after the bank is made whole, of course – rather than go through the foreclosure process.

And further support comes from the folks over at Core Logics who recently put out a paper suggesting that about 42% of all owners in the forbearance program bought their home before 2012 and they have, unsurprisingly, built up a sizeable chunk of equity in their homes, with median equity – even after they cover any missed payments – of almost $100,000.

Of course, it’s reasonable to say that this may all sound good, but what about owners who didn’t buy a long time ago and therefore have less equity.

Well, their data shows that 43% of owners in forbearance bought between 2013 and 2018 and they too have benefitted from prices rising and have an average of more than $87,000 in equity – again after accounting for missed payments.

And even the newest owners – those who purchased their home in 2019 or later – and they represent 15% of all homes in forbearance – well they still have an average of over $65,000 in equity.

The bottom line is that, in broad terms, a typical homeowner in forbearance could – with relative ease – cover the costs of selling a home and still have some equity left over.

Will foreclosures rise this year – yes, they will – but given all the facts I have just shared with you, I see it as being more of a trickle than a flood.

Well, there you have it.


In Conclusion

As far as I can see, all the data shows that we are in a very different place today than we were in the 2000’s and I find it highly unlikely that we will see a repeat of the events we saw back then.

Down payments are higher; credit quality is higher; and demographic demand for ownership housing remains robust and – quite likely will only grow as the nation’s Millennials continue to reach prime home buying. Remember that 9.6 million of them will be turning 30 over the next 2 years alone.

But, as I said in my opening comments, the pace of price growth that we’ve seen over the last year or so is clearly unsustainable and must, at some point start to slow, if only to allow incomes to catch up.

In fact, I am already seeing some tentative signs of this with the percentage growth in list prices starting to soften in several markets across the country which should start to ease the pace of sale price appreciation.

But I am afraid that I just don’t see a national downturn in home values occurring – unless banks decide to significantly loosen their underwriting criteria, but I find that very hard to believe.

Thank you for sticking with me during this rather long video. I do hope that you found it of some interest.

As always, if you have any questions or comments about today’s topic, please feel free to reach out. I would love to hear from you.

In the meantime, thank you again for watching, stay safe out there, and I look forward to visiting with you again, next month.

Bye now.
Market Trends • April 26, 2021

April Market Update – Matthew Gardner Report

Hello there and welcome to the April edition of Mondays with Matthew. I’m Windermere Real Estate’s Chief Economist, Matthew Gardner

There were a lot of rich, housing-related datasets released this month so let’s get going.

And first up, I want to look at mortgage applications.

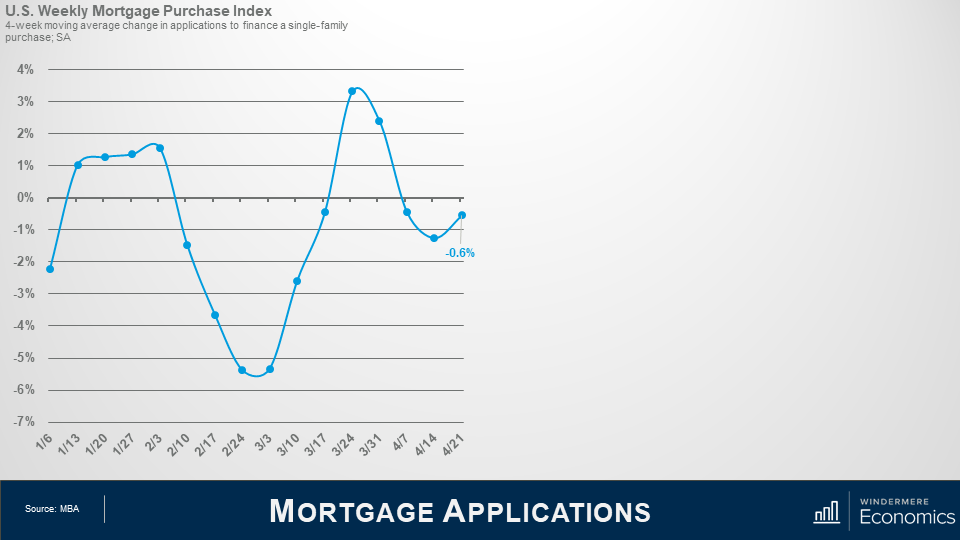
Line graph showing mortgage purchases from January 6th to April 21st. The line shows that applications slowed before picking back up at the end of February into March. Then the trend falls in early April and in the last 2 weeks of April the line shows an increase in applications again.

Source: MBA

You may remember last month we discussed what was going on with mortgage rates as they had started to trend higher beginning in the New Year. Well, as rates rose, you can see here that mortgage applications slowed before picking back up in at the end of February, which was interesting as rates were still rising at that time.

And for those who find it curious that applications picked up even as rates were rising, well it was partly because buyers started to believe that rates would not be headed back down, and they wanted to get locked in for fear that they would continue trending higher.

Now, this pattern did reverse at the end of March as rising rates started to take a toll on would be buyers and affordability issues started to come more into play, but as mortgage rates pulled back in April, applications picked up again – albeit modestly.

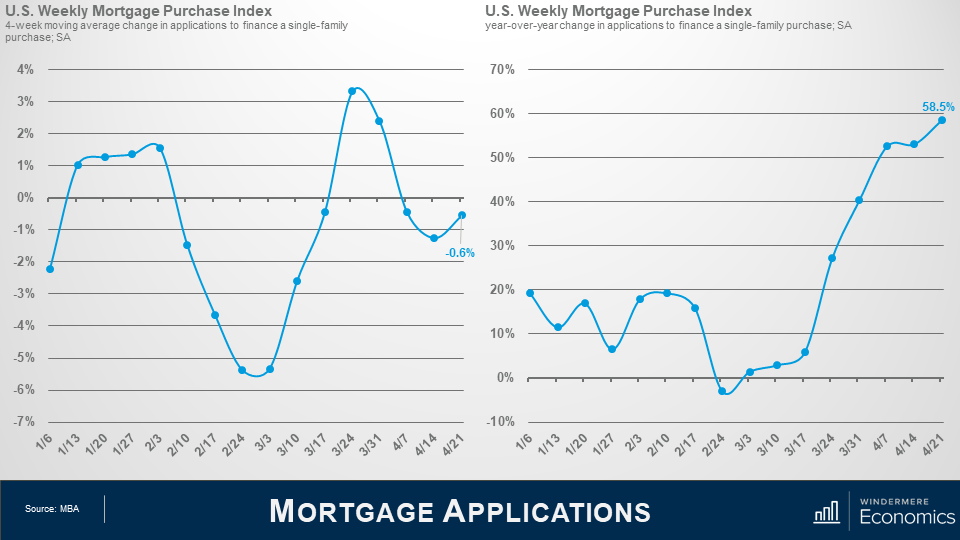
Next to the Mortgage purchase graph, on the right we see the weekly mortgage purchase index which looks at the year over year data. Here we see that since this time last year, there are 58.2 percent more mortgage applications.

Source: MBA

But when we take a look at the data on a year-over-year basis.  Well, WOW!

Applications were up by over 58%! But remember what happened in March of last year? Who can forget….?

And its therefore really not surprising to see this kind of spike, but, I would caution you all that almost any dataset that compares current numbers to those seen a year ago – well, they are likely to paint far too rosy a picture, and one that is removed from reality.

Something to be aware of.


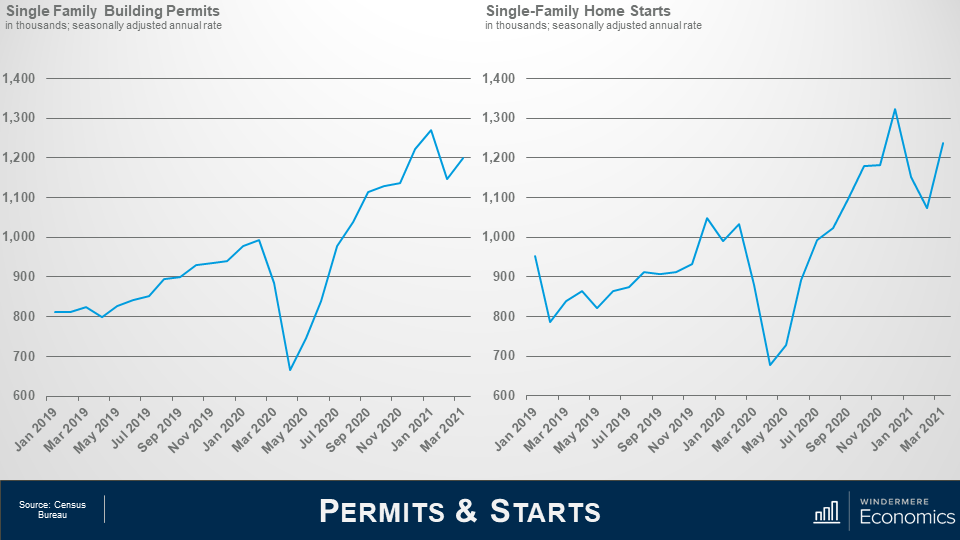
Next up, we got several datasets regarding the new home market March and we will start off with permits and starts.

Two line graphs next to each other. The one on the left shows the single family building permits from January 2019 to March 2021. Overall the trend is upward, with a large dip from March to May 2021, but they soon recover as if that dip never happened. From January to March 2021 there was another small dip, but there’s already proof of improvement back from that. On the right, the graph shows the single family home starts, again overall starts have increased since January 2019 to March 2021, with a few peaks and valleys in between, included a recent dip from November 2020 to February 2021, but they’re back on the rise since then.

Source: Census Bureau

Following the pullback in permit applications that was seen in February, builders were more optimistic in March with single family permits up by 4.6% on the month and 35.6% higher than a year ago – but don’t forget what we just said about year over year data!

Looking at housing starts – well they pulled back in January and February, but also saw a solid 15% monthly increase in March.

Interestingly, there was a massive spike in starts in the mid-west where they were up by 109% month-over-month, but they were actually down by over 12% out here in the west.

I would also let you know that the number of homes under construction rose by 1.6% versus February and this was particularly pleasing given that construction costs remain very elevated.

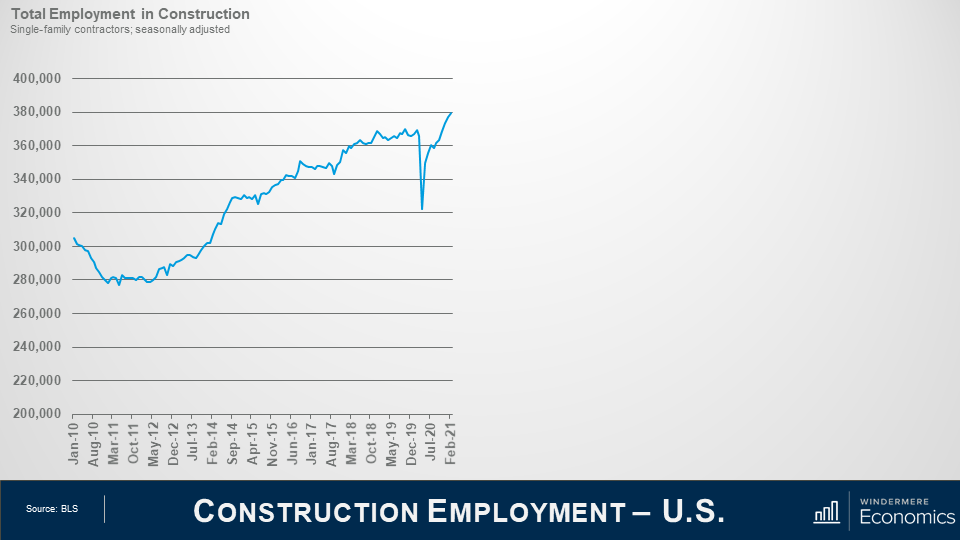
And it hasn’t just been material costs that have been hitting home builders, they have also seen significant pressures with labor costs and here’s why…

One line graph to the left, with space to the right for another. Data shows total employment in construction from January 2010 to February 2021. Overall trend shows constant growth since 2012, with a sharp dip in 2020 from the pandemic.

Source: BLS

This chart shows how many people are employed in the construction of single-family homes and, at face value, it looks pretty good with constant growth seen since 2012 – of course, ignoring the impact of the pandemic but….

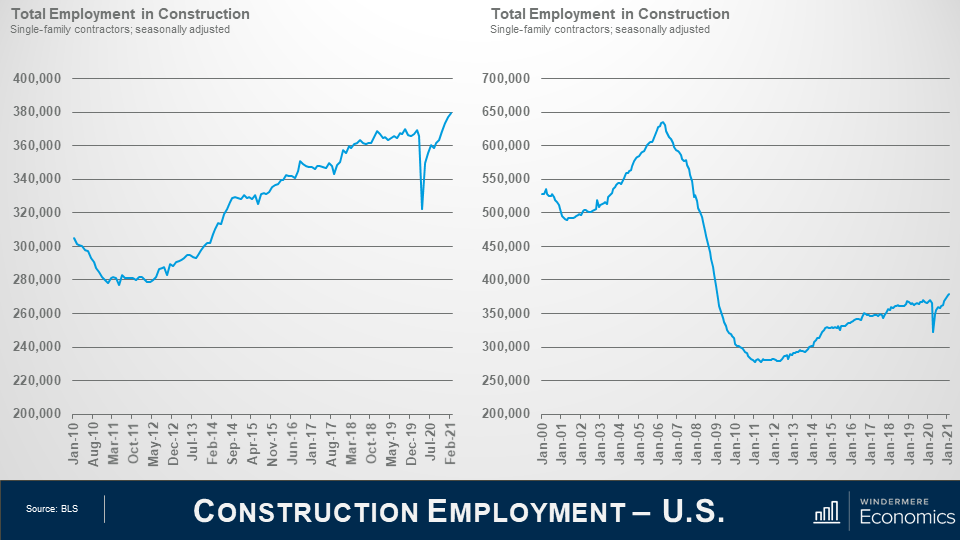
On the same slide as the total employment in construction, to the right of that graph there’s total employment in Construction from January 2000 to January 2021, which shows an overall trend of decrease in jobs. A peak in 2006 soon falls to a very low valley in 2012.

Source: BLS

Looking at a longer timeline, it doesn’t paint as good a picture. At its peak in 2006, there were almost 650,000 people employed building homes, but the number today is just 60% of that.

Of course, there are fewer homes being started today than there were back in those halcyon days but starts today aren’t 40% lower, so the job market remains tight. In fact, there are over 260,000 job openings in the construction sector. Of course, not all of them are for the single-family construction market, but we do know that builder’s cost of labor is rising and that, in concert with higher land and material costs continue to impact builder’s ability to bring homes to market that are relatively affordable as the increase in costs is transferred directly into the price that a home must sell for and that brings me to data on new home listings, sales and prices in March.

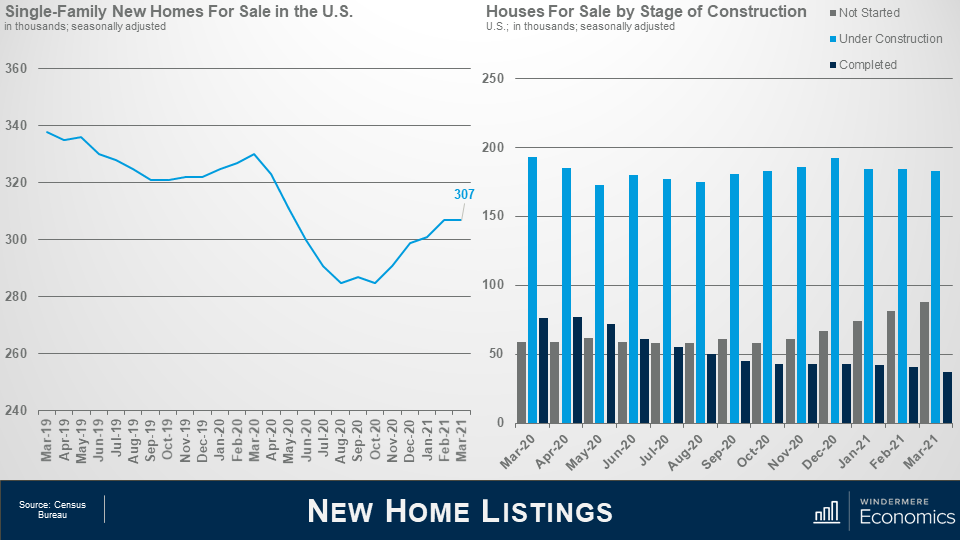
Two graphs side by side, on the left is a line graph showing the Single Family New Homes for Sale in the US. This graph shows an overall trend of decrease in new homes for sale from 2019, but increased since the lowest point in the fall of 2020. On the right is a bar graph showing the houses for sale by stage of construction. The grey line represents “not started,” light blue represents “Under construction,” and navy represents “completed.” The light blue lines showing under construction are constantly the highest bars hovering between 150,000 and 200,000.

Source: Census Bureau

Even with new housing permits and starts rising significantly the seasonally adjusted estimate of new houses for sale at the end of March was 307,000. This represents a supply of 3.6 months at the current sales rate.

The number of new homes for sale was down by 7% from a year ago, but I do expect that the increase in permits and starts bodes well for this arena, and I do expect to see more listings come online over time.

If you look at the chart to the right, you will notice that the number of homes for sale that have yet to be started continues to rise. This is because builders want some certainty that the home will be sold, and it’s, therefore, easier to sell before you build it.

Source: Census Bureau

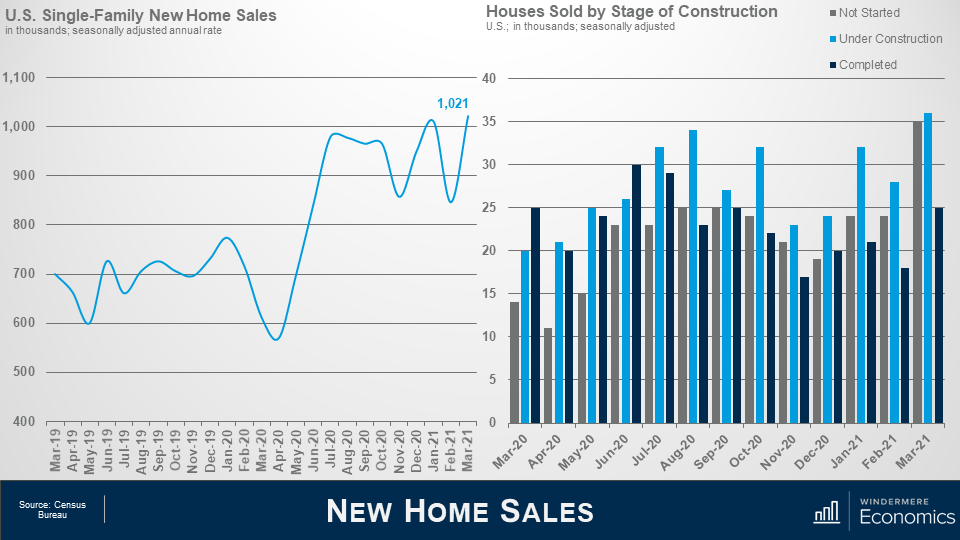
And when we look at sales, well they rise by 20.7% in March to an annual rate of over 1 million units and clearly rebounded from the previous month when we saw a massive drop as severe winter storms wreaked havoc across much of the country.

Interestingly, you will see that as many homes sold that hadn’t yet started as were under construction. Clearly, demand is robust to the degree that buyers willing to commit to buying a home that hasn’t yet been built.

The median new home sale price came in at $330,800 – that’s down by 4.4% on the month but 0.8% higher than a year ago.

Source: NAR

OK – now we have covered the new home market, let’s take a look at how the resale market fared in March.

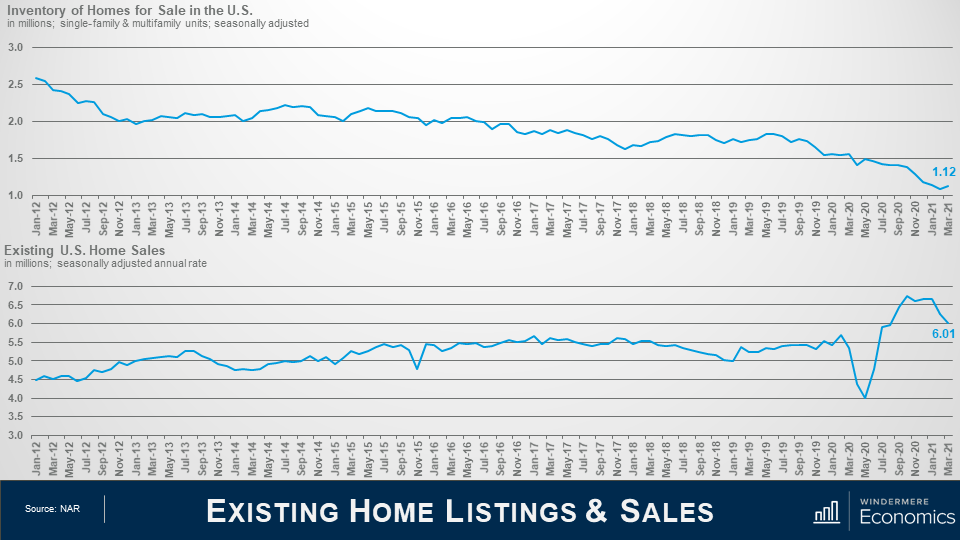
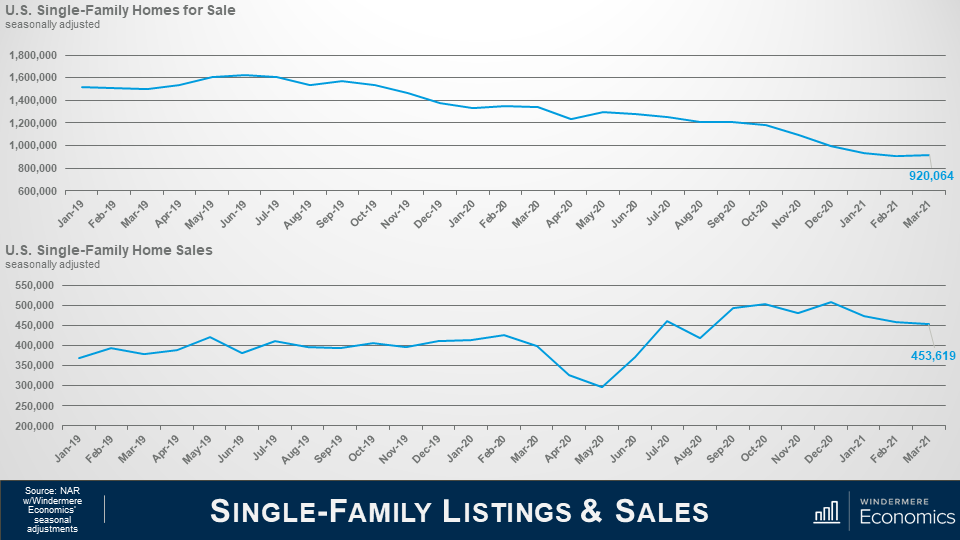
The number of homes for sale remains at almost historically low levels with marginally more than 1 million units on the market. Now there maybe some of you out there who say that is inaccurate as NAR is reporting 1.07 million homes for sale, and you’d be absolutely correct.  But I have adjusted the data to account for seasonality, so it is slightly different.

Anyway, with such limited choice across the country, it wasn’t a surprise to see sales pulling back, with the total number of closings running at an annual rate of 6 million units – that’s down by 3.7% month over month, and down by 12.3% when compared to March of 2020.

Am I worried about this? No, I am not. Why? Well, as I just mentioned, just look at the inventory numbers.  With little choice, it’s not at all surprising to see sales pull back but I would add that the market still hit 6 million transactions and that was in the face of the increase in mortgage rates that we saw last month so, to tell you the truth, I was actually a little surprised to see that the number held above that 6 million level.

Source: NAR

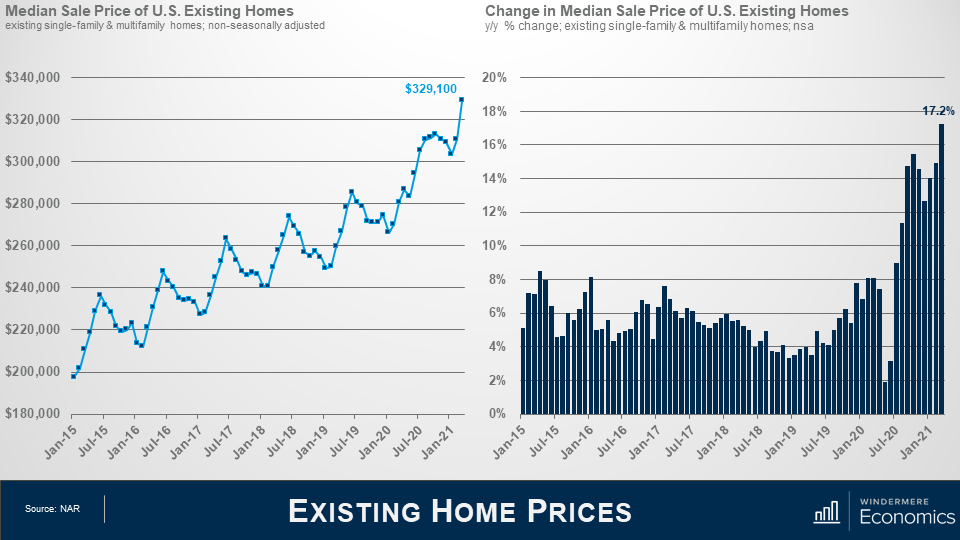
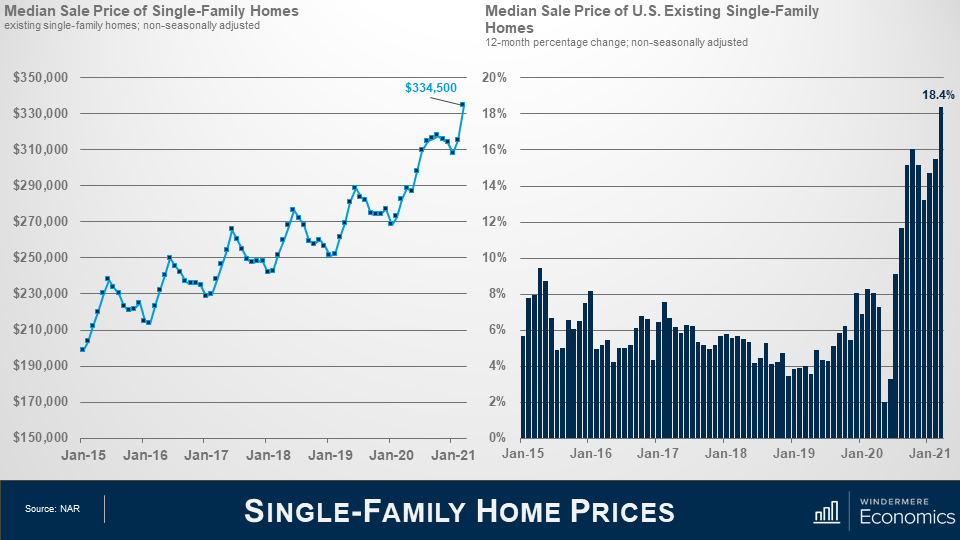
But even as sales pulled back a little, prices didn’t, and more records were broken with the median sale price hitting an all-time high, and year-over-year price growth above 17% was another record shattered.

Source: NAR

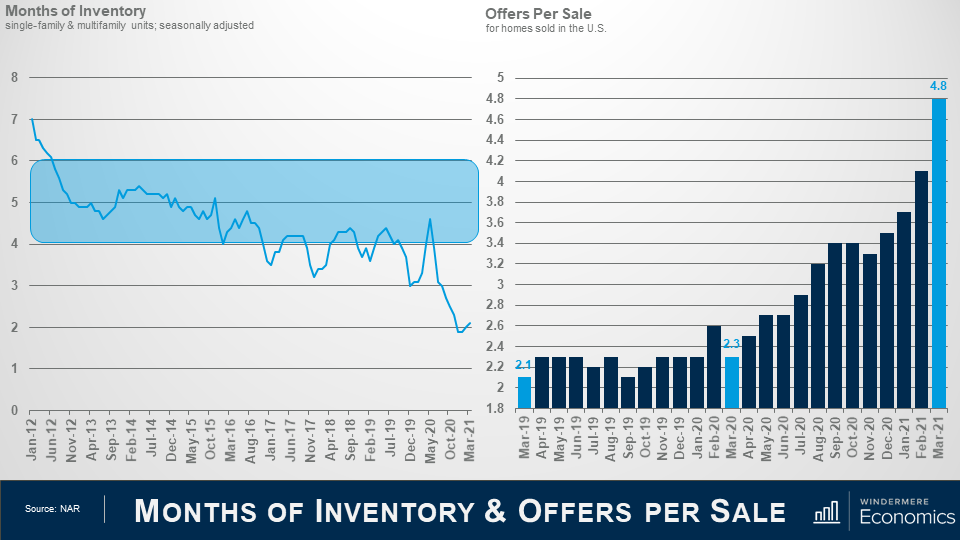
And if you need further proof that there is little to be concerned about when it comes to sales pulling back, you only need to look at these charts.  Low supply, but still very robust demand has months of supply at levels that indicate a highly unbalanced market. Nationally, I like to see somewhere between 4 and 6 months of supply, not 2.1…

But look at the right. For every offer accepted in March, there were 3.8 additional offers, and I would also tell you that the average length of time it took to sell a home in March was just 18 days and that’s down by one day from February but down by eleven days when compared to a year ago.

Surely if demand was waning, wouldn’t the number of offers be going down, and days on market going up?

Source: NAR with Windermere Economics seasonal adjustments

And when we separate out the single-family market, you can see that listings notched very slightly higher – up by 1.2%, but the level is still close to an all-time low with listings down by over 31% year over year.

As far as sales are concerned, well they also pulled back a little and were down by 1.3% versus February but were 14% higher year over year.

Source: NAR

And as we discussed earlier, even with lower sales activity, sale prices are still rising at a very rapid pace and are now over 18% higher than seen a year ago and a remarkable 6.2% higher than seen in February.

The median price also broke above $330,000 for the first time.

Source: NAR with Windermere Economics Seasonal Adjustments

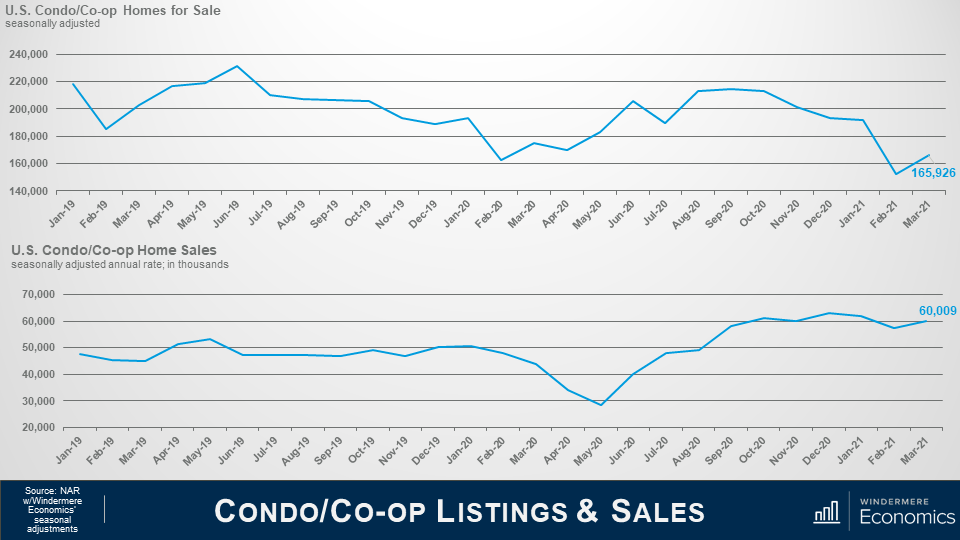
Moving on to the condominium market, we saw listings rise as the pandemic took hold, and there were concerns back then that we were at the start of a systemic increase in listings with people fleeing cities over fears of COVID-19, as well as the ability to work remotely, but the increase soon wore off, even if it rise by 9% in March when compared to February, but there were 5.1% fewer listings than seen a year ago.

But on the sales front – and with listings rising – we saw demand for those homes with sales up by 5% versus February and 36.4% higher than seen in March of 2020.

Source: NAR

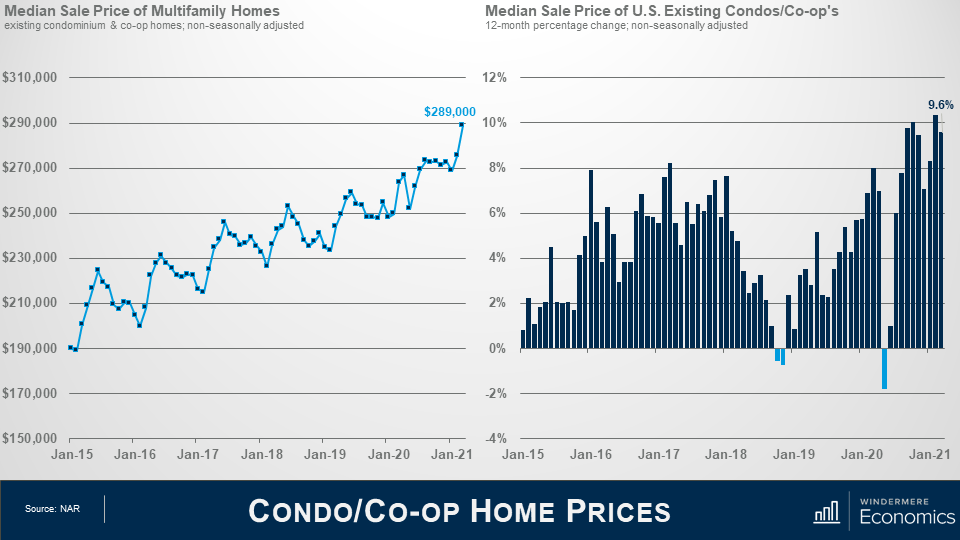
In a similar fashion to single-family prices, sale prices for condominium units saw a spike in price in March and were up by 4.9% versus February and almost 10% higher than seen a year ago.

Although you will see that annual sale price growth did turn negative last May – due to COVID – it is actually rare to see this. We did see a tiny drop back in 2018 but you will likely remember that mortgage rates were rising then and knocking on the door of 5%.

Anyway, since last May, sale prices have picked back up very nicely and worries of any significant drop in condo prices appears to be overblown.

As far as the ownership market is concerned, I am far less worried that mortgage rates have been ticking higher than I am that there are just not enough homes for sale to meet demand.

We had seen some growth in the new construction arena – and that took just a tiny bit of heat off the resale arena – but demand continues to exceed supply, and that is pushing prices higher and affordability issues have already started to appear in several markets across the country.

At some point, we will see price growth slow, but I think that it will be far more to do with affordability limitations than it will rising mortgage rates.

So, there you have it. My thoughts on the housing market in March.

As always, if you have any questions or comments about the numbers, we have looked at today, feel free to reach out. I would love to hear from you.

In the meantime, thank you for watching, stay safe out there, and I look forward to visiting with you again, next month.

Bye now.
First Time Buyer • Home Buying • April 20, 2021

Why is This Home Called a Condo?

If you have done any house hunting around Seattle in the past few years you may have come across a property that feels like a single-family home, but is confusingly classified as a condo. These homes are called “detached condos” and are becoming quite common.

What is a Detached Condo?

Detached condos, also called  “free-standing condos” or “ground condos”,  have been a development style in planned communities for several years and are increasingly being brought into cities as infill construction. Detached condos are a way to gently add density to neighborhoods that have historically only had single-family homes. In general, the main difference between traditional single-family homes, and detached condos is that these homes have a Homeowner’s Association (HOA) and Codes, Covenants and Restrictions (CC&R’s). The HOA and CC&R’s will help to protect the new owners’ investment in the long run, as their property and neighboring properties will be well maintained.

What Does the HOA Cover?

The HOA will typically be jointly managed by the homeowners, though they have the option to hire a management company if they choose. When the HOA is established there will be several documents created including a Public Offering Statement, HOA Bylaws, and a Property Map. The Condo Documents will identify the rules and boundaries of the detached condo units. All of these documents should be available to buyers before they put in an offer on the home.

Typically, the HOA dues on detached condos are very small and only cover very basic items. The Budget should outline the initial HOA fees for each homeowner. If they choose, the homeowners can elect to share additional expenses such as utilities, yard maintenance, etc. that are not pre-determined in the Condo Documents, through the HOA.

What Do I Actually Own?

Ownership of these homes is very similar to ownership of a traditional single-family property. Each homeowner owns their entire structure as well as their individual parcel unit as described in the Condo Declaration. Each unit will have a separate Tax ID Number and the homeowners will only pay the taxes as assessed for their individual parcel and unit. Additionally, any land between each unit parcel, if any, is considered common space, which may consist of driveways or walkways.

Just like with a single-family home, each homeowner is responsible for the maintenance of both the interior and the exterior of their own property, which includes the land within their designated parcel. Any interior updates or changes are fully up to the discretion of each homeowner, though decisions that would change the exterior of the home will typically need to be agreed upon with the other HOA member(s).

What About Utilities?

With detached condos, there may be some shared utilities such as water and gas, that can either be paid jointly through the head of the HOA, or separately metered by a third-party company if the homeowners decide to go that route. Typically, electricity will be separately metered to each unit, though depending on how the property was built, this may also be a shared utility. This is another item that will be explained in the Condo Documents.


In most circumstances, detached condos are extremely similar to single family homes, with only very minor differences. Each owner owns the home and the land within their own parcel and is responsible for taking care of both the interior and exterior of their own property. Savvy buyers are finding detached condos to be a great way to gain access to unattached homeownership through this type of property purchase.


* This is not intended as legal advice, consult an attorney with legal questions.
Home Maintenance • Selling • March 15, 2021

The Benefits of a Pre-Listing Inspection

Previously published on the Windermere Blog by Sandy Dodge

Pre-listing inspections can help sellers better understand the condition of their home before putting it on the market. They can also strengthen a home’s appeal to potential buyers and help to streamline the offer process, which is especially important in competitive markets. However, pre-listing inspections can also open sellers up to added liability. Talk to your Windermere agent to understand if conducting a pre-listing inspection is right for your home.


What is a Home Inspection?

Conducted by a licensed home inspector, a home inspection is a detailed review of the condition of a home and property. Inspectors examine everything from a home’s electrical work and sewage to its heating and cooling systems, searching for any evidence of damage or structural issues that may affect its value. By having your home inspected before you sell, you’ll have the chance to discover whether it needs any repairs or upgrades.


Pre-Listing Inspections

Pre-listing inspections not only help identify repairs, but they can also make the selling process more efficient. A pre-listing inspection discloses a home’s condition to buyers up front and gives them confidence that the seller is being transparent about any possible issues. This can save significant time for both buyers and sellers, especially in competitive markets where there are multiple offers on the table.

Something for sellers to keep in mind is that if a home in a competitive market does not provide a pre-inspection report, buyers may be hesitant to make an offer knowing the time it takes to perform an inspection and the fact that they are likely competing against several other buyers who are willing to waive this step.


The Benefits of a Pre-Listing Inspection

Home inspections give a good baseline of your home’s condition. The information gathered during this process is exactly the kind of in-depth knowledge that buyers want to know when considering placing an offer on a home.

Since buyers will know right away what repairs are needed, they can factor them into their initial offer, as opposed to discovering them during the inspection contingency and getting entangled in negotiations. Being forthcoming about your home also reduces the chances of an offer falling through and the buyer walking away.

An added benefit of a pre-listing inspection is that it helps your real estate agent more accurately price the home and enables them to market it with the knowledge that everything is being presented in the most transparent way possible.


If you have any questions about home inspections or any of the steps in the selling process, please reach out to me!


Footer

Home Maintenance • Home Renovations • March 15, 2021

How to Prevent Water Damage to Your Home

Previously published on the Windermere Blog – Written by Sandy Dodge

Water is constantly coursing through your home, flowing in and out of drain pipes, sinks, tubs, and showers. Numerous systems in our homes are dependent upon water, but the minute it runs rampant it begins to cause damage. The consequences of water damage run the gamut, from rotted drywall and mold growth to serious structural issues. The following guide will help you understand what you can do to prevent water damage in your home.


How to Prevent Water Damage

Leaks

Leaks soften wood, which invites all sorts of unwanted activity from termites, while simultaneously creating a perfect habitat for mold and mildew growth. To prevent leaks, keep your drains healthy by frequently cleaning out your drain strainers and refraining from dumping grease down your drains. Check to make sure none of your drains are leaking and if need be, repair or replace your p-traps. Drips, dark stains around your pipes, and discoloration on your ceilings and walls are all strong indicators that a leak has sprung. If you notice an inexplicable spike in your water bill, this is also a sign of a potential leak. By identifying these signs, you can begin repairs right away and stop the water damage in its tracks.

Gutter drainage

A home with weak gutter drainage is an open invitation for water damage to occur. Cleaning your gutters routinely is the best way to prevent them from clogging, which helps to avoid damage to your siding and foundation. Make sure your downspouts expel the gutter water away from your house parallel to the ground. Take a trip to the hardware store for downspout extensions and elbows to make sure that water won’t build up around your home’s foundation, especially if you live in a rainy climate.

Sump pump

Your sump pump can be your saving grace should a water emergency occur. Sump pumps move excess groundwater away from your home, preventing it from infiltrating your basement or crawl space. They are connected to the Ground Fault Circuit Interrupter (GFCI) electrical outlet, which protects it from electrical shorts. There are two ways to test your sump pump. The first is by pouring in enough water to raise the float. If it’s working properly, the pump should activate and begin removing water from its pit. The other method is to unplug the pump’s power and plug it back in. If it does not turn on, it requires repair or replacement.

More

There are some additional steps you can take to prevent water damage to your home. Inspect your roof to identify any damaged shingles or cracks. While you’re up on the roof, take a look at your chimney. Repair any cracked or broken bricks and consider a chimney cap if you don’t already have one in place.


Water damage can be harmful to your home and your finances. Even the smallest leak can snowball into larger problems if neglected. By following the steps to prevent water damage, you’ll know if your home needs repairs before it’s too late. For more advice on preventing damage to your home, read our guides to wildfire and winter storm prevention.


Footer

Uncategorized • March 4, 2021

A Brief History of Women in the U.S. Real Estate Industry

March is Women’s History Month

and, so I thought it would be fitting to create a timeline of the history of Women in Real Estate. It is notable that though we were initially excluded from taking part in real estate, not only as business professionals, but also as land owners, women now make up a healthy majority of professionals in the industry. Women have blazed trails as leaders and have formed influential organizations such as the Women’s Council of Realtors and continue to shape the industry.


I hope you enjoy this brief history, feel free to share amazing accomplishments by women in this field.

Timeline of women in US real estate


Footer
Uncategorized • March 3, 2021

What Is a Craftsman Home?

By by Sandy Dodge – previously on the Windermere Blog

The Craftsman home has a distinct look and definitive features, whose origins date back to nineteenth-century Britain. Their popularity can be attributed to the simple ideas behind their design and their focus on functional living.


Types of Craftsman Homes

Craftsman Bungalow

For many people, the type of Craftsman home that immediately comes to mind is the Craftsman Bungalow. Bungalows are of modest size, with a covered porch and tapered columns supporting a low-pitched roof. Often, you’ll see these homes with double gable roofs, where the front porch will extend beyond the house. Bungalows are typically one or one-and-a-half stories.

Four Square Craftsman

The Four Square Craftsman is a larger, two-story version of the Bungalow, meant for bigger families. Accordingly, their construction saw a significant increase as soldiers returned from World War I. Their name comes from their design of four rooms on the first and second floors, one in each corner.

Prairie Craftsman

The Prairie Craftsman style can be traced back to renowned American architect Frank Lloyd Wright. Known for their low profile and powerful horizontal lines, Prairie Craftsman homes typically have an open floor plan and harmonize with their surrounding landscape.

Mission Revival

Borrowing greatly from the style of the Prairie Craftsman, the Spanish influences of the Mission Revival make it a unique Craftsman home. Typical features include a stucco exterior, arches, and open interior spaces with terracotta detailing. If someone points out a house as a “Spanish Bungalow,” you’re looking at a Mission Revival Craftsman.


Characteristics of Craftsman homes

Exterior

Highly identifiable, Craftsman homes share many commonalities, but seemingly, no two are identical. A covered porch with tapered columns is the first indicator you’re looking at a Craftsman. The roofs are low-pitched with overhanging eaves, giving way to exposed rafters underneath. It’s common for the windows to be double-paned, while the front doors will typically contain their panes in the upper section.

Interior

Known for their open floor plans, ample seating, and plenty of built-in shelving, the inside of a Craftsman home is a comfortable place to be. Reflecting the hard-working nature of their style, you’ll find plenty of handcrafted woodwork, stonemasonry, and brickwork throughout the interior. Fireplaces are often the central feature of Craftsman living rooms.


Now that you know a bit more about the Craftsman home and how to identify it, look for examples of these characteristics in your neighborhood. Due to the widespread popularity of the Craftsman style, chances are you won’t have to look too far.


Footer

First Time Buyer • Home Buying • February 24, 2021

The Importance of Pre-Approval

Written by Sandy Dodge – previously posted on the Windermere Blog

To set yourself up for a smooth and successful home purchase, getting pre-approved is perhaps the most productive first step you can take. It strengthens your buying credibility, informs your home search, and speeds up the closing process.


The Pre-Approval Process 

There is an important distinction to made between two important steps of your mortgage application process: pre-qualification and pre-approval. They are similar in that they both help to inform your financial standing, but there are key differences between the two.

Pre-qualification

Pre-qualification is the first step in your mortgage application process. It will help you to understand the approximate loan amount you can expect to qualify for. You’ll begin by sharing your financial information—debt, income, assets, etc.—with you bank or lender. After reviewing the information, the bank or lender will give a loan estimate. The process is relatively simple, only taking a few business days to process.

Pre-approval

The pre-approval process is more involved than pre-qualification. After submitting a mortgage application, your lender will require all the necessary info to conduct a thorough credit history check and review of your financial health. Getting pre-approved will give you a better idea of how much you can borrow, estimated monthly costs, and what interest rates you can expect on your loans. Mortgage pre-approvals are typically valid for 60 to 90 days.


Benefits of Pre-Approval

Credibility

The truth is, each home on the market can only go to one buyer. To maximize the chance that your offer is accepted, sellers need to know that your offer is serious. Getting pre-approved shows that you are financially prepared and, in the event that your offer is accepted, there will be no hold ups in obtaining your mortgage. This assurance is what sellers want to know about their potential buyers, especially in a seller’s market.

Home search

Not only does pre-approval help to bolster your case as a buyer, but it also Indicates your affordable price range. By knowing your budget, you will be able to hone your home search and start preparing offers, eliminating any potential wasted time looking at houses you can’t afford.

Closing process

Once your offer is accepted, you’ll be counting down the days to move-in. Unfortunately, the closing process can often drag on, leaving buyers feeling like they’re in post-purchase limbo. Pre-approval will speed up the closing process, since the mortgage approvals have already been taken care of, allowing you to focus on next steps like appraisals and inspections.


When to Get Pre-Approved

Being financially prepared for a home purchase is a solid indicator that you’re ready to go about getting pre-approved, but what does that look like? Buying a house means taking on serious debt, so it’s important to either have your remaining debt paid off or have a clear path to becoming debt-free before getting pre-approved. Having adequate savings for a down payment is a sign that you’re ready to make your offer. For any questions about the pre-approval process and to get connected to a mortgage professional, contact me, your Windermere agent.


Footer

Market Trends • January 28, 2021

Top 10 Things to Look Out for in 2021 – From Windermere’s Chief Economist Matthew Gardner

Top 10 Provided by Windermere’s Chief Economist Matthew Gardner

1. Economic Growth Will Pick up – But Not Until the Summer

I am expecting solid employment gains in 2021, but growth is likely to start in earnest in the second half of the year once the vaccine has been more widely distributed. I believe job growth will increase as spending rises. Once people feel more comfortable going out again it will give a much-needed boost to the economy and job market.

2. The Move to the Suburbs is Real – But Don’t Get Carried Away!

There has been a lot of talk about a COVID-19 induced flight away from cities and into the suburbs and outlining areas. While I do believe there will be a migration away from some of our core cities this year, most people won’t move far as working from home will not be a full-time situation for many workers who will split their time between home and office.

3. Not all Apartment Markets are Created Equal

Apartment owners in pricey markets across the country will continue to suffer in 2021, but after many years of being overlooked, smaller cities will perform rather well. It is my prediction that apartment developers will start to turn their attention toward suburban markets and away from many of these larger cities. We haven’t seen that in over a decade.

4. The Luxury Housing Market Will Continue to Perform Very Well

The luxury housing market, which performed far better than anyone expected in 2020, will continue to be robust in 2021. The primary reason for this will be interest rates. Jumbo mortgage rates saw a spike at the start of the pandemic but have since dropped significantly which is benefitting luxury home buyers. Furthermore, as the country starts to reopen postCOVID, I believe we will see a rebound in foreign buyers.

5. Cities will Start to Pay More Attention to Zoning (at Long Last!)

Although it won’t happen overnight, I am hopeful that discussions around zoning changes will start to pick up steam this year. I believe there will be more attention by legislators on increasing the supply of land for residential construction and many will do this by adjusting current zoning policies to free up more land on which to build.

6. Adaptive Reuse Will Gain More Traction

Developers will pay more attention to the potential for repositioning existing buildings, as well as ground-up construction. Although I don’t see developers looking to convert office buildings into residential uses, I am watching hotels (mainly motels and inns), which are likely going to continue to be hard hit for years, and alternative uses may make sense. Additionally, strip malls and regional malls may become of interest to developers. I believe there is the potential for some regional malls to be converted into mixed-use projects, while strip malls may get rezoned into single residential use.

7. What’s important in a post-COVID-19 home?

Due to COVID-19, homeowners want more space and builders have taken note. After several years of building smaller homes, the average new home size is actually starting to increase. I also expect to see buyers listing high-speed internet access as a requirement rather than an option (mainly in rural areas), and open floor plans that were once a must, will be replaced with more room separation.

8. Worries About Forbearance are Overblown.

I do not anticipate a wave of foreclosures following the end of forbearance, and foreclosures that do occur will have a limited impact on the broader housing market. A lot of people fear that when forbearance expires, we will see a tsunami of foreclosed homes and that this increase in supply will lead to homes values dropping. I say it won’t happen, and here’s why. Firstly, the number of homes in forbearance is already down by 43% from its May peak. The trend is headed in the right direction. Secondly, I believe as owners start to get back to work again, many will be able to either refinance their loans, or work with their lenders to extend the term of their mortgages in order to make up missed payments and avoid foreclosure. I would also add that if there are homeowners who can’t get back on track, they will sell their homes to keep the equity they have built. In most markets across the country, there will be enough buyer demand that they will be able to get out from under forbearance by selling and paying off the mortgage and missed payments. All that said, I am a little worried about urban condominium owners who are in forbearance, as the supply of these properties is already on the rise, causing price growth to soften relative to single-family homes. This may be an obstacle to some condo owners who want to get out from under forbearance by selling.

9. Mortgage Rates Will Rise – But Don’t Worry

Rates for 30-year conforming mortgages have broken below all-time lows 16 times since the pandemic started; however, they are unlikely to drop much more. That said, I don’t anticipate them rising too much this year, averaging around 3.2%.

10.US Home Sales Will Rise Significantly, but Price Growth Will Moderate

There will be even more demand from buyers this year, and the good news is that I expect listings to increase as people look to relocate. This will allow 2021 home sales to rise to a level we haven’t seen since 2006! Big players in the market to buy this year will be renters who will choose to move out of expensive cities because they are working from home and no longer need to live close to their office. My forecast is for existing home sales to rise by 7.7% in 2021 to around 6.2 million units. I will also predict that home prices will increase in 2021 but slowly rising mortgage rates, combined with affordability constraints in many markets, will act as a headwind and slow appreciation. Average prices will rise by a relatively modest 4.1% in 2021.

Top 10 Provided by Windermere’s Chief Economist Matthew Gardner

Home Renovations • January 21, 2021

Incorporate Pantone’s Color of 2021 Into Your Home

For the second time ever, Pantone’s Color of the Year is actually two colors: Ultimate Gray and Illuminating Yellow. Ultimate Gray is emblematic of natural elements that stand the test of time, while Illuminating Yellow is a cheerful sunshine yellow, symbolizing energy and clarity.

Here are some ways you can harness this color harmony in your home.

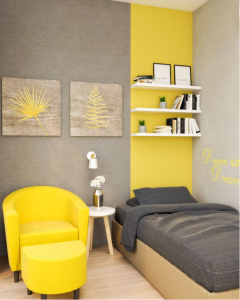
Brighten Your Bedroom

With a foundation of Ultimate Gray, Illuminating yellow will brighten your bedroom, livening up the space and radiating positivity. Mix and match different furniture and accent wall combinations to get the right balance of sunny yellow and solid gray.

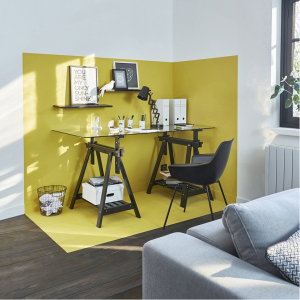
Refresh Your Home Office

Home offices have become more important than ever. As working from home continues in 2021, your remote workspace is the perfect location to add in Pantone’s Color of the Year. We all could use some added stimulation to keep our workdays going smoothly and productively. Use Illuminating to add some colorful accents or to paint your wall, balance it out with some Ultimate Gray, and let the positivity fill your home office. A modern home office with a yellow wall.


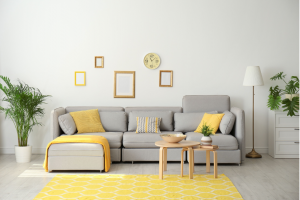
Accents In Your Living Room

Pantone’s Illuminating is a perfect accent color for your home. Incorporate this energetic sunshine yellow in your living room in the form of decorative throw pillows, blankets, and accent décor pieces like vases and curtains. Ultimate Gray is a perfect color for large furniture items and will help to balance out the tone of your living room. It provides a neutral backdrop, which gives you the freedom to decorate brightly.

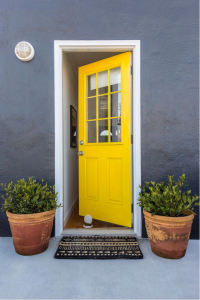
Make A Statement With Your Front Door

Your front entrance plays a significant role in the first impressions of your home. What better way to use Pantone’s striking yellow than a front door makeover? Illuminating yellow presents an opportunity to bring a little sunshine to your family and guests every time they approach. Ultimate Gray as both a wall color and an accent color will help to solidify your new, strikingly optimistic front door. Accent pieces like house numbers, your mailbox, and plant pots will help create harmony between the two colors. A yellow front door against a gray wall.


Read more about this year’s color trends and how you can incorporate them into your home here: 2021 Paint Color Trends