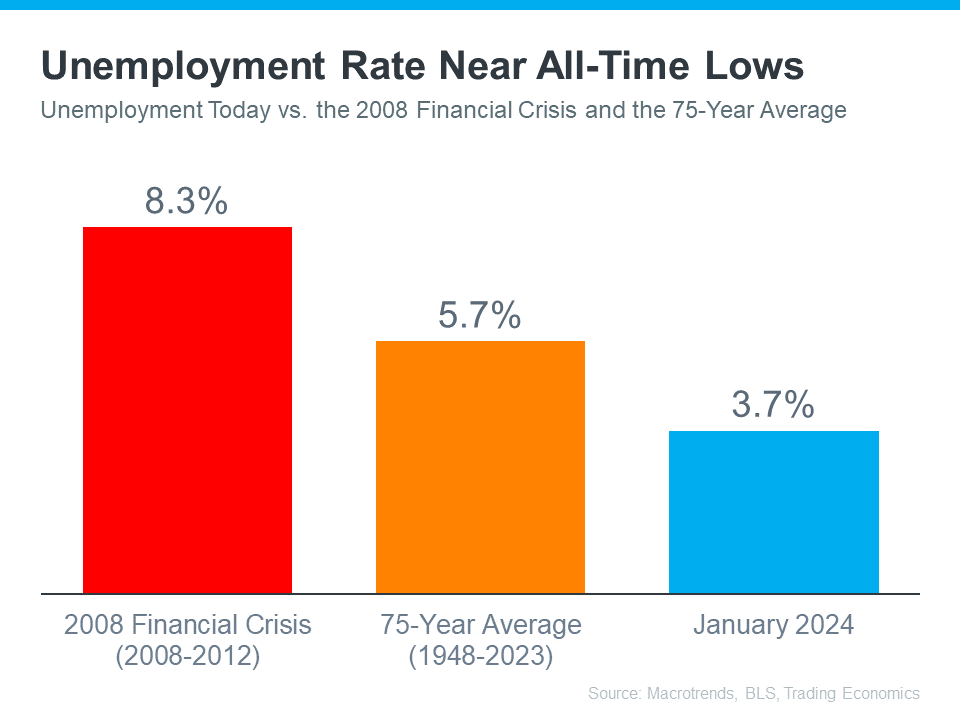First Time BuyerHome Buying June 26, 2026

New Construction Homes for Sale in East Bellevue: The East Bellevue Collection

Looking for a new construction home in Bellevue, Washington? The East Bellevue Collection is a limited offering of five luxury single-family homes designed for buyers who want modern construction, spacious living, and one of the Eastside’s most desirable locations by esteemed home builder, Thomas James Homes

Each home features approximately 3,010 square feet, 5 bedrooms, 4.5 bathrooms, premium designer finishes, and thoughtfully designed living spaces that balance everyday comfort with elegant entertaining.

Whether you’re relocating to Bellevue, moving up to a larger home, or searching for new construction close to major employers like Microsoft, Amazon, and Downtown Bellevue, this collection offers a rare opportunity to compare multiple homes with the same highly desirable floor plan.


What Is the East Bellevue Collection?

The East Bellevue Collection consists of five newly constructed luxury homes located throughout East Bellevue.

Rather than choosing from a single available home, buyers can compare five homes built from the same award-worthy floor plan while selecting the lot, location, and move-in timeline that best fits their lifestyle.

One home is fully completed and professionally staged as a model home, while the remaining homes are in various stages of construction and nearing completion.

This allows buyers the flexibility to move immediately or reserve a home that will be ready in the coming months.

View all available homes here


Luxury Home Features

Every home in the East Bellevue Collection includes:

  • Approximately 3,010 square feet
  • Five spacious bedrooms
  • Four and one-half bathrooms
  • Open-concept great room
  • Designer kitchen with premium finishes
  • Large island ideal for entertaining
  • Dedicated dining space
  • Flexible living areas perfect for home offices or guest suites
  • Luxury primary suite
  • Energy-efficient new construction
  • Attached garage
  • Contemporary architecture
  • Builder warranty for added peace of mind

These homes are designed for today’s buyers, offering open living spaces, abundant natural light, and high-quality finishes throughout.


Why Buy a New Construction Home in Bellevue?

Many buyers choose new construction because it offers advantages that are difficult to find in older homes.

Benefits include:

  • Modern floor plans designed for today’s lifestyles
  • Lower maintenance during the first several years of ownership
  • Improved energy efficiency
  • New appliances and mechanical systems
  • Current building standards
  • Builder-backed warranties
  • Contemporary finishes without the need for remodeling

For many homeowners, purchasing new construction means spending more time enjoying the home and less time planning renovations.


Why East Bellevue?

East Bellevue has become one of the most sought-after residential areas on the Eastside.

Residents enjoy convenient access to:

  • Downtown Bellevue
  • Microsoft
  • Amazon
  • Google
  • Meta
  • Bellevue’s shopping and dining
  • Parks and trails
  • Highly regarded schools
  • Interstate 405 and State Route 520
  • Seattle via Interstate 90

Its central location makes East Bellevue especially attractive for technology professionals, executives, entrepreneurs, and families seeking both convenience and long-term value.


Which Home Is Right for You?

Because all five homes share the same exceptional floor plan, buyers can focus on choosing the home that best fits their needs.

Some buyers want immediate occupancy.

Others prefer purchasing before completion to allow additional planning before moving.

Having multiple homes available provides flexibility that is rarely found in Bellevue’s new construction market.


Compare All Five Available Homes

I’ve created a detailed presentation featuring every home currently available in the East Bellevue Collection, including photos, availability, and property details.

Explore the complete East Bellevue Collection here.


Frequently Asked Questions

How many homes are available?

The East Bellevue Collection currently includes five luxury new construction homes.

Are all of the homes the same?

They share the same thoughtfully designed floor plan, but each home has its own location, lot characteristics, and construction timeline.

Can I tour the homes?

Yes. A professionally staged model home is available for private tours, making it easy to experience the layout, finishes, and craftsmanship before comparing the remaining homes.

Are the homes move-in ready?

One home is completed and staged, while the others are in various stages of construction and nearing completion.

Who are these homes ideal for?

These homes are well suited for executives, growing families, relocation buyers, professionals working on the Eastside, and anyone seeking luxury new construction in Bellevue.


Schedule a Private Tour

If you’re considering purchasing a new construction home in Bellevue, I’d be happy to help you compare the available homes, explain the construction process, discuss builder warranties, and help you determine which property best fits your needs.

Whether you’re relocating from another state or simply moving across town, my goal is to provide expert guidance throughout the buying process and help you make a confident, informed decision.

Contact me today to schedule a private tour of the East Bellevue Collection.

Marnie Oshan, MBA 206-659-8116 marnie@windermere.com

Home BuyingMarket Trends September 12, 2025

How Interest Rates Are Affecting the Seattle Real Estate Market—and Why Now Could Be the Right Time to Buy

The Seattle real estate market has always been dynamic, but the past couple of years have brought especially dramatic shifts. Rising interest rates have slowed some of the frenzied activity we saw during the pandemic-era boom, creating a new landscape for buyers, sellers, and investors alike.

The Role of Interest Rates in Today’s Market

Higher interest rates have undoubtedly impacted affordability, keeping some buyers on the sidelines. Yet, this has also led to less competition and more opportunities for those still in the market. Homes are no longer receiving dozens of offers within days, and buyers now have the breathing room to carefully evaluate their options, negotiate terms, and secure properties that would have been out of reach just a short time ago.

Why New Construction Is a Smart Play Right Now

New construction is particularly appealing in this environment. Builders in the Seattle area are motivated to sell, and many are offering incentives such as rate buydowns, closing cost credits, or upgrade packages that can offset today’s borrowing costs. For owner-occupants, this means the chance to purchase (and in some circumstances – customize) a brand-new home while taking advantage of builder perks. For investors, new construction offers modern, low-maintenance properties in high-demand neighborhoods—making them easier to rent and hold for long-term appreciation.

A Window of Opportunity

Markets move in cycles, and today’s environment represents a potential window of opportunity. While rates may seem high compared to recent history, they are still below long-term averages, and experts predict they could ease in the future. Buying now allows you to lock in a property at today’s prices—before demand surges again when rates decline.

Let’s Talk About Your Options

Whether you’re considering a personal move or exploring investment opportunities, Seattle’s current market offers unique advantages for those who act strategically. If you’d like to discuss what’s happening right now, evaluate specific neighborhoods, or explore new construction opportunities, I’d be happy to walk you through your options.

📩 Reach out to me anytime to start the conversation—I’m here to help you navigate Seattle’s real estate market with confidence.

Home BuyingMarket Trends August 12, 2025

Why Now Is a Smart Time to Invest in Seattle Real Estate 🏘

Why Now Is a Smart Time to Invest in Seattle Real Estate 🏘

And Why You Need the Right Agent in Your Corner

Seattle’s real estate market is shifting—and for savvy investors, that spells opportunity.

While headlines may focus on elevated rates or price fluctuations, serious investors know these transitional markets are when smart money moves. With inventory growing, seller concessions increasing, and rental supply tightening, the current environment offers rare leverage for those ready to buy.

But timing the market is only part of the equation—who you work with matters just as much as when you buy.


Why This Market Works for Investors

📉 Prices Are Stabilizing, Not Crashing

Median home prices in Seattle softened to ~$839K as of August 2025. Sellers are more negotiable, with increased room to buy below market—or at least with favorable terms.

🏗 Inventory Is Up, Competition Is Down

With listings up over 37% year-over-year, the market has shifted from frenzy to strategy. That means better selection and a chance to structure deals that protect your return.

💰 Motivated Sellers Are Offering Incentives

Nearly 70% of sellers in early 2025 provided buyer concessions—closing cost credits, inspection repairs, or permanent rate buydowns—allowing you to improve your cash flow or reduce out-of-pocket costs.

📈 Rent Growth Ahead

Seattle’s new apartment construction has dropped dramatically—permits are down 50%, and completions are slowing. That tightening pipeline, paired with a growing renter pool, makes rental properties increasingly valuable, especially in supply-constrained neighborhoods.


How I Help You Capitalize on This Market

As an investor-friendly Realtor with deep expertise in new construction, I bring more than just market knowledge—I bring strategic insight, strong builder relationships, and an investor’s mindset to every deal.

Here’s how I can help:

✅ I Understand the Numbers

I don’t just show homes—I analyze deals. Whether you’re looking at cash flow, long-term appreciation, rent comps, or exit strategy, I help you make decisions based on data, not emotion.

✅ I Know the Builders—and the Incentives

Having worked closely with builders across the greater Seattle area, I know which ones are offering rate buydowns, closing cost credits, early-phase pricing, and inventory discounts. This can make a major difference in your return.

✅ I Source Off-Market & Early-Release Opportunities

Through my builder and developer network, I can connect you with new construction homes and townhomes before they hit the MLS—giving you first-mover advantage in prime locations.

✅ I Advocate Like an Investor—Because I Am One

Your goals are my goals. I approach each transaction with a long-term perspective, ensuring your investment aligns with the market cycle and your personal strategy.


Seattle’s Current Market = Strategic Entry Point

Even with rates in the 6.6%–6.9% range, many investors are buying now with a refinance strategy in mind. And with sellers more flexible and competition lower, you can negotiate better terms, protect your downside, and position for strong long-term growth.

If you’re looking for:

  • New construction homes with rental upside

  • Turnkey or light value-add properties

  • Homes in up-and-coming urban infill areas

  • Multi-door investments or ADU/ DADU-eligible lots

  • Creative financing or concession-rich deals

…I can help you identify, evaluate, and negotiate with confidence.


Final Thought

Seattle’s market is in a moment of recalibration—not retreat. And for investors, that’s where the best opportunities are born.

Let’s talk if you’re ready to explore what’s out there. Whether you’re a first-time investor, scaling your portfolio, or 1031 exchanging into something more hands-off, I’ll help you navigate the current market and make strategic moves now that will pay off for years to come.

Whether you are ready to invest or just thinking about it, feel free to reach out! Call or text 206-659-8116 or email me at marnie@windermere.com

First Time BuyerHome BuyingMarket TrendsUncategorized August 5, 2025

Why Now is a Great Time to Buy New Construction—Can Even Be Cheaper Than Renting!

In today’s market, buying a home might seem like a bold move—but when it comes to new construction, it could be one of the smartest financial decisions you make. Despite high interest rates and lingering affordability concerns, a perfect storm of builder incentives and softening rents in certain areas has created a rare window of opportunity for buyers. In some cases, you can actually buy for less than it costs to rent.

Here’s why now is the right time to consider new construction:

  1. Monthly Mortgage Payments Are Beating Rent

In several neighborhoods, the cost of renting a comparable home or apartment has climbed while builders have adjusted pricing and added concessions. With the right financing and incentives, you could own a brand-new home for less than you’re currently paying in rent—and build equity while doing it.

For example, a buyer using a builder-paid interest rate buy-down could see their monthly payment drop significantly, tipping the scales in favor of ownership, especially in suburban or growing metro areas where rents have remained high.

  1. Builder Incentives Are Reducing Real Costs

To attract buyers in a slower market, many builders are offering substantial incentives that directly reduce your monthly costs. These can include:

  • Permanent rate buy-downs (e.g., 30-year fixed rates as low as 4.99% in some cases)
  • Closing cost credits

These incentives help offset higher interest rates, making new homes more affordable than resale options—and, surprisingly, even cheaper than many rentals.

  1. New Construction = Long-Term Savings

Beyond just the purchase price, new construction homes come with long-term cost advantages:

  • Lower maintenance: Everything is brand new, from the roof to the HVAC.
  • Builder warranties: Most new construction warranties will include the structure and major systems and even some cosmetic items.
  • Energy efficiency: New homes are built to modern energy codes, often including double-pane windows, high-efficiency appliances, and smart home features that reduce monthly utility bills.
  1. Inventory Is Available—But It Won’t Last Forever

After a multi-year housing shortage, we’re finally seeing more inventory in the new construction market. Builders are motivated to sell, but as the market stabilizes and rates eventually come down, demand is expected to rebound—and prices and competition will likely follow. The best deals are available now, while supply is strong and incentives are generous.

Bottom Line

If you’ve been sitting on the sidelines, now is the time to take a serious look at new construction. Between builder-paid rate buy-downs, closing cost assistance, and today’s rent-versus-buy math, buying a new home could actually cost you less each month than continuing to rent. That’s a rare opportunity in any market—and one worth exploring before it passes.

Want to find out if buying new construction is cheaper than renting in your area? Let’s connect and run the numbers together. You can reach me at marnie@windermere.com or 206-659-8116


Home BuyingMarket Trends January 30, 2025

January Market Update

As of January 2025, Seattle’s housing market continues to exhibit dynamic trends, particularly in the realm of new construction. The city remains a focal point for both buyers and investors, driven by its robust economy and desirable living conditions.

Current Market Overview

According to Redfin, the median listing home price in Seattle stands at approximately $885,000, with properties typically spending around 75 days on the market.

This reflects a balanced market, offering opportunities for both buyers and sellers.

New Construction Trends

In 2023, Seattle achieved a significant milestone by completing 12,853 new homes, marking a 21% increase over the previous year and setting a new record for housing production.

Despite this surge, the city faces challenges in maintaining this momentum. Recent data indicates a decline in construction permits, suggesting potential slowdowns in future housing availability.

As of late 2024, builder sentiment in Seattle was measured at 44 out of 100, a notable decrease from the peak of 91 in March 2022, though slightly improved from the previous year. Additionally, the construction sector reported 129,300 jobs in November 2024, a reduction of 4,500 positions compared to the same month in 2023.

Factors Influencing New Construction

Several elements contribute to the current state of new construction in Seattle:

  • Geographic Constraints: Seattle’s unique topography, bordered by water and mountains, limits available land for development, inherently restricting housing supply.
  • Zoning Regulations: Existing zoning laws further constrain the development of new housing projects, particularly in central urban areas.
  • Economic Considerations: While construction costs have seen a slight decrease of 1.8% year-over-year, they remain elevated, impacting the feasibility of new projects.

Looking Ahead

The combination of high demand and limited supply continues to characterize Seattle’s housing market. The recent decline in construction permits may signal a future slowdown in housing availability, potentially leading to increased competition among buyers and sustained upward pressure on prices.

For stakeholders in the real estate sector, staying informed about these trends is crucial. Engaging with local policymakers, advocating for thoughtful zoning reforms, and exploring innovative construction methods could play pivotal roles in addressing the housing challenges facing Seattle in the coming years.

If you are interested in either buying or selling in Seattle, or just want to learn more about the housing market, feel free to reach out to me anytime. You can reach me at marnie@windermere.com or 206-659-8116.

Market Trends March 5, 2024

Why We Aren’t Headed for a Housing Crash

Why We Aren’t Headed for a Housing Crash

If you’re holding out hope that the housing market is going to crash and bring home prices back down, here’s a look at what the data shows. And spoiler alert: that’s not in the cards. Instead, experts say home prices are going to keep going up.

Today’s market is very different than it was before the housing crash in 2008. Here’s why.

It’s Harder To Get a Loan Now – and That’s Actually a Good Thing

It was much easier to get a home loan during the lead-up to the 2008 housing crisis than it is today. Back then, banks had different lending standards, making it easy for just about anyone to qualify for a home loan or refinance an existing one.

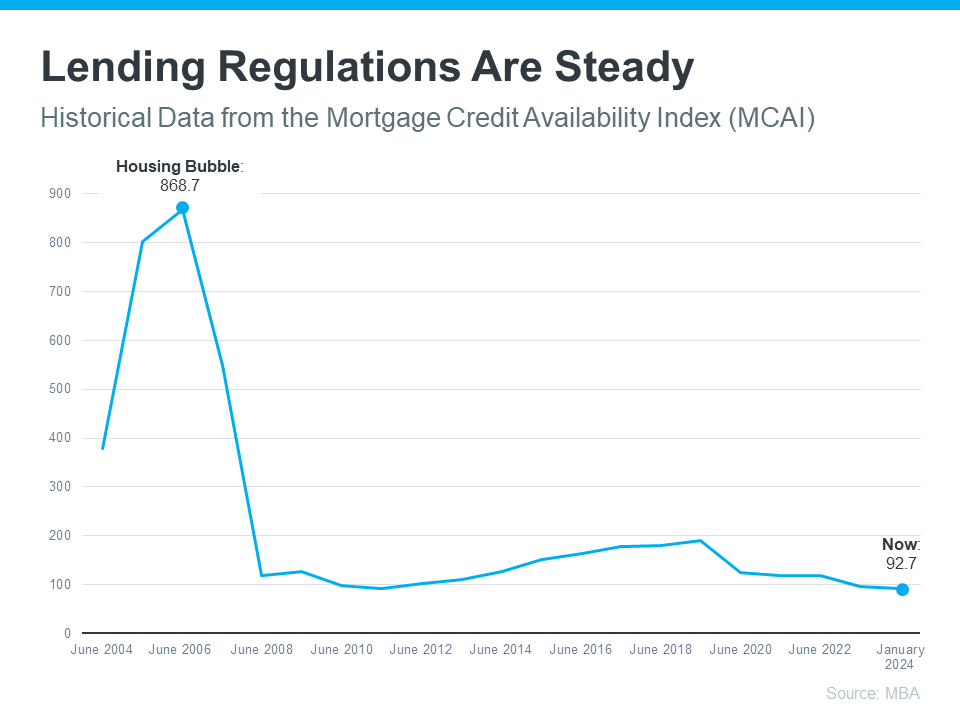
Things are different today. Homebuyers face increasingly higher standards from mortgage companies. The graph below uses data from the Mortgage Bankers Association (MBA) to show this difference. The lower the number, the harder it is to get a mortgage. The higher the number, the easier it is:

a graph showing a line going up

The peak in the graph shows that, back then, lending standards weren’t as strict as they are now. That means lending institutions took on much greater risk in both the person and the mortgage products offered around the crash. That led to mass defaults and a flood of foreclosures coming onto the market.

There Are Far Fewer Homes for Sale Today, so Prices Won’t Crash

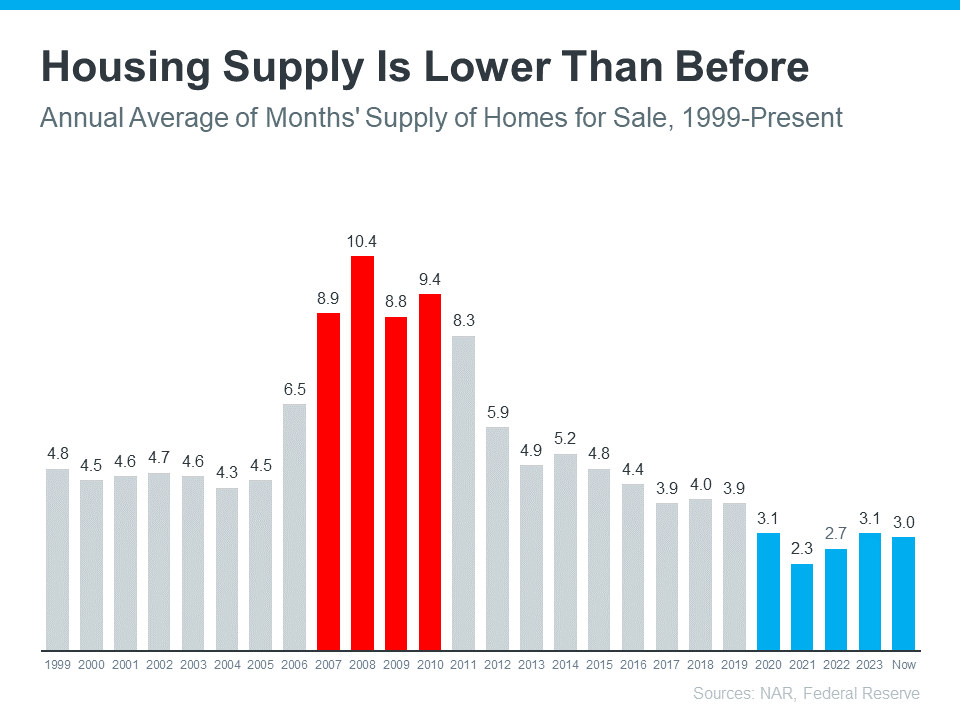
Because there were too many homes for sale during the housing crisis (many of which were short sales and foreclosures), that caused home prices to fall dramatically. But today, there’s an inventory shortage – not a surplus.

The graph below uses data from the National Association of Realtors (NAR) and the Federal Reserve to show how the months’ supply of homes available now (shown in blue) compares to the crash (shown in red):

a graph of a number of people

Today, unsold inventory sits at just a 3.0-months’ supply. That’s compared to the peak of 10.4 month’s supply back in 2008. That means there’s nowhere near enough inventory on the market for home prices to come crashing down like they did back then.

People Are Not Using Their Homes as ATMs Like They Did in the Early 2000s

Back in the lead up to the housing crash, many homeowners were borrowing against the equity in their homes to finance new cars, boats, and vacations. So, when prices started to fall, as inventory rose too high, many of those homeowners found themselves underwater.

But today, homeowners are a lot more cautious. Even though prices have skyrocketed in the past few years, homeowners aren’t tapping into their equity the way they did back then.

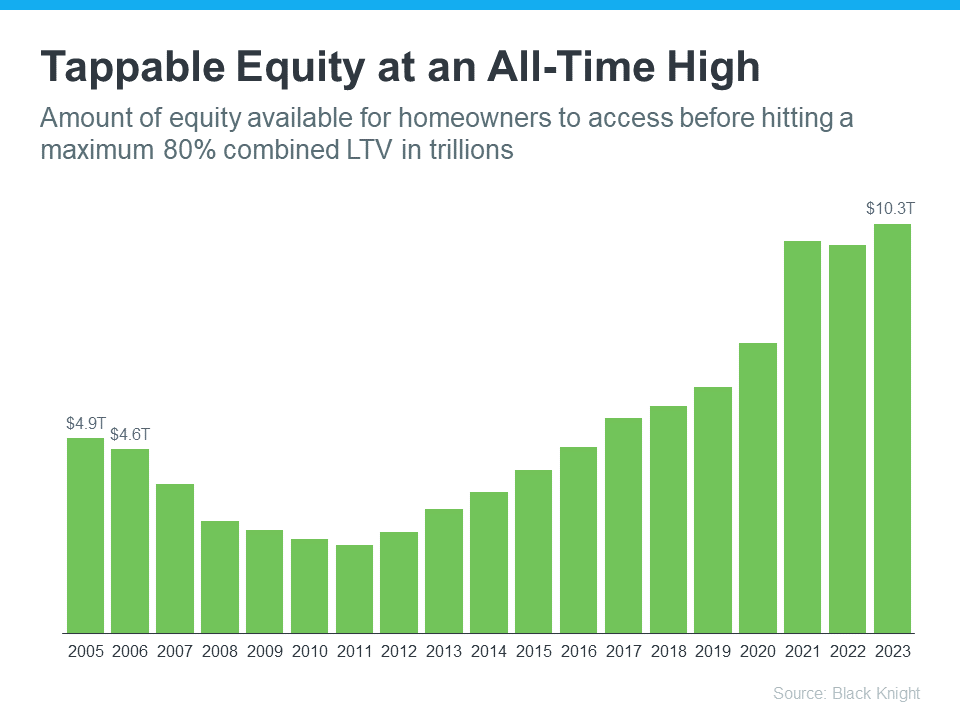
Black Knight reports that tappable equity (the amount of equity available for homeowners to access before hitting a maximum 80% loan-to-value ratio, or LTV) has actually reached an all-time high:

a graph of a growing graph

That means, as a whole, homeowners have more equity available than ever before. And that’s great. Homeowners are in a much stronger position today than in the early 2000s. That same report from Black Knight goes on to explain:

“Only 1.1% of mortgage holders (582K) ended the year underwater, down from 1.5% (807K) at this time last year.”

And since homeowners are on more solid footing today, they’ll have options to avoid foreclosure. That limits the number of distressed properties coming onto the market. And without a flood of inventory, prices won’t come tumbling down.

Bottom Line

While you may be hoping for something that brings prices down, that’s not what the data tells us is going to happen. The most current research clearly shows that today’s market is nothing like it was last time.

Market Trends March 5, 2024

Why There Won’t Be a Recession That Tanks the Housing Market

Why There Won’t Be a Recession That Tanks the Housing Market

There’s been a lot of recession talk over the past couple of years. And that may leave you worried we’re headed for a repeat of what we saw back in 2008. Here’s a look at the latest expert projections to show you why that isn’t going to happen.

According to Jacob Channel, Senior Economist at LendingTree, the economy’s pretty strong:

“At least right now, the fundamentals of the economy, despite some hiccups, are doing pretty good. While things are far from perfect, the economy is probably doing better than people want to give it credit for.”

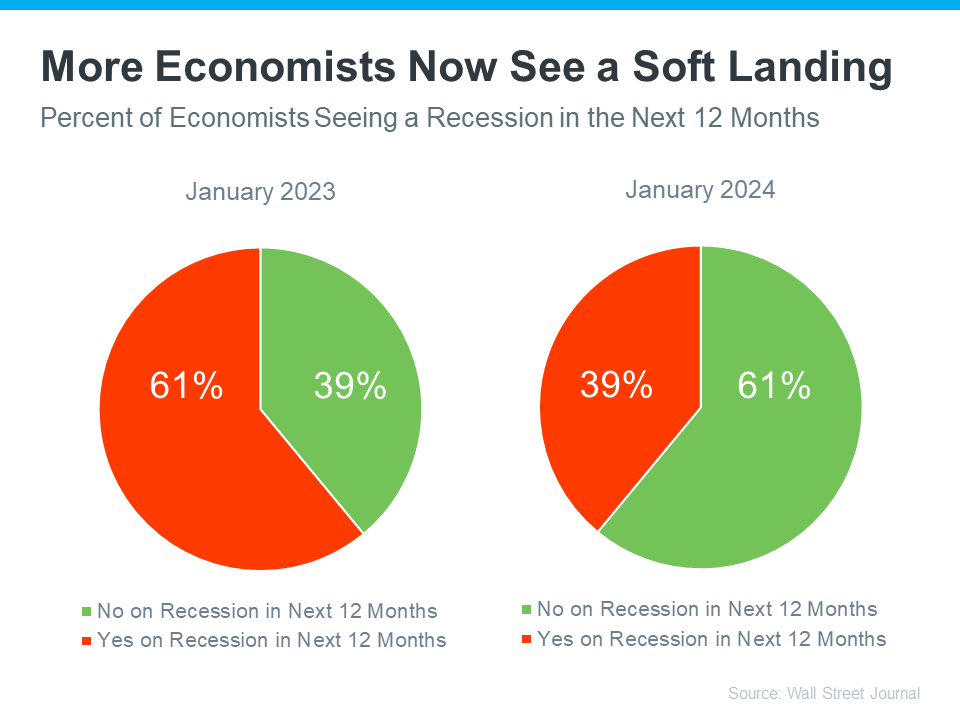
That might be why a recent survey from the Wall Street Journal shows only 39% of economists think there’ll be a recession in the next year. That’s way down from 61% projecting a recession just one year ago (see graph below):

a graph of the economic growth of the economy

Most experts believe there won’t be a recession in the next 12 months. One reason why is the current unemployment rate. Let’s compare where we are now with historical data from Macrotrends, the Bureau of Labor Statistics (BLS), and Trading Economics. When we do, it’s clear the unemployment rate today is still very low (see graph below):

a graph of a graph showing the number of employment rate

The orange bar shows the average unemployment rate since 1948 is about 5.7%. The red bar shows that right after the financial crisis in 2008, when the housing market crashed, the unemployment rate was up to 8.3%. Both of those numbers are much larger than the unemployment rate this January (shown in blue).

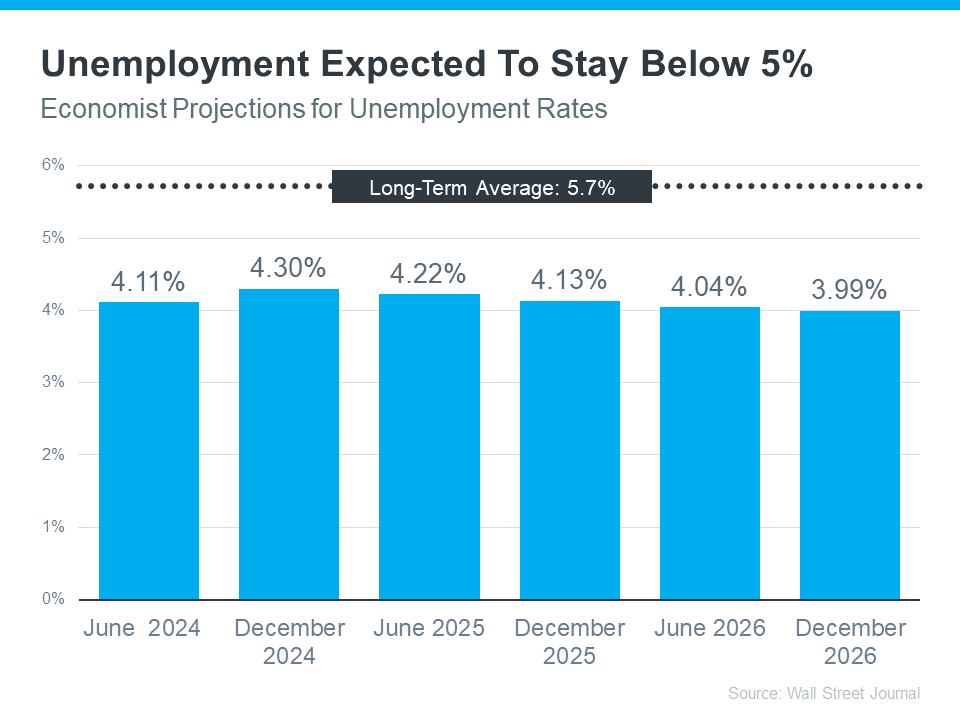
But will the unemployment rate go up? To answer that, look at the graph below. It uses data from that same Wall Street Journal survey to show what the experts are projecting for unemployment over the next three years compared to the long-term average (see graph below):

a graph of blue bars

As you can see, economists don’t expect the unemployment rate to even come close to the long-term average over the next three years – much less the 8.3% we saw when the market last crashed.

Still, if these projections are correct, there will be people who lose their jobs next year. Anytime someone’s out of work, that’s a tough situation, not just for the individual, but also for their friends and loved ones. But the big question is: will enough people lose their jobs to create a flood of foreclosures that could crash the housing market?

Looking ahead, projections show the unemployment rate will likely stay below the 75-year average. That means you shouldn’t expect a wave of foreclosures that would impact the housing market in a big way.

Bottom Line

Most experts now think we won’t have a recession in the next year. They also don’t expect a big jump in the unemployment rate. That means you don’t need to fear a flood of foreclosures that would cause the housing market to crash.

Market Trends April 28, 2022

Q1 2022 Western Washington Real Estate Market Update

The Gardner Report – Q1 2022

The following analysis of select counties of the Western Washington real estate market is provided by Windermere Real Estate Chief Economist Matthew Gardner. We hope that this information may assist you with making better-informed real estate decisions. For further information about the housing market in your area, please don’t hesitate to contact me.

REGIONAL ECONOMIC OVERVIEW

The post-COVID job recovery continues. Though data showed the number of jobs dropped in January, February saw gains that almost offset the jobs lost the prior month. As of February (March data is not yet available), the region had recovered all but 47,000 of the more than 300,000 jobs lost due to the pandemic. Of note is that employment levels in Grays Harbor, Thurston, San Juan, and Clallam counties are now above their pre-pandemic levels. In February, the regional unemployment rate rose to 4.1% from 3.7% in December. Although this may be disconcerting, an improving economy has led more unemployed persons to start looking for a job, which has pushed the jobless rate higher. I expect the regional economy to continue expanding as we move into the spring and summer, with a full job recovery not far away.

HOME SALES

  • In the first quarter of 2022, 15,134 homes sold, representing a drop of 5.8% from the same period a year ago, and down 31.7% from the fourth quarter.
  • Yet again, supply-side constraints limited sales. Every county except Snohomish showed lower inventory levels than a year ago.
  • Sales grew in five counties across the region but were lower across the balance of the counties contained in this report. Compared to the fourth quarter, sales were lower across all market areas.
  • The ratio of pending sales (demand) to active listings (supply) showed pending sales outpacing listings by a factor of 6.7. Clearly, the significant jump in mortgage rates in the first quarter has not yet impacted demand. Rather it appears to have stimulated buyers partly due to FOMO (Fear of Missing Out)!

HOME PRICES

  • Although financing costs have jumped, this has yet to prove to be an obstacle to buyers, as prices rose 16.4% year-over-year to an average of $738,152. Naturally, there is a lag between rates rising and any impact on market prices. It will be interesting to see what, if any, effect this has in the next quarter’s report.
  • Compared to the same period a year ago, price growth was again strongest in San Juan County, but all markets saw prices rising more than 10% from a year ago.
  • Relative to the final quarter of 2021, all but Kitsap (-2.7%), Mason (-1.5%), Skagit (-1.8%), Jefferson (-6.3%), and Clallam (-0.1%) counties saw home prices rise.
  • The market remains supply starved. While increases in “new” listings suggest that more choice is coming to market, it remains insufficient to meet demand.


MORTGAGE RATES

Average rates for a 30-year conforming mortgage were 3.11% at the end of 2021, but since then have jumped over 1.5%—the largest increase since 1987. The surge in rates is because the market is anticipating a seven- to eight-point increase from the Federal Reserve later this year.

Because the mortgage market has priced this into the rates they are offering today, my forecast suggests that we are getting close to a ceiling in rates, and it is my belief that they will rise modestly in the second quarter before stabilizing for the balance of the year.

DAYS ON MARKET

  • It took an average of 25 days for a home to go pending in the first quarter of 2022. This was 4 fewer days than in the same quarter of 2020, but 2 days more than in the fourth quarter of 2021.
  • Snohomish, King, and Pierce counties were the tightest markets in Western Washington, with homes taking an average of 11 to 15 days to sell. The greatest drop in market time compared to a year ago was in San Juan County, where it took 23 fewer days for homes to sell.
  • All but five counties saw average time on market drop from the same period a year ago, but the markets where it took longer to sell a home saw the length of time increase only marginally.
  • Quarter over quarter, market time dropped in Snohomish, King, and Pierce counties. Jefferson and Clallam counties also saw modest improvement. In the balance of the region the length of time a home was on the market rose, but seasonality undoubtedly played a part.

CONCLUSIONS

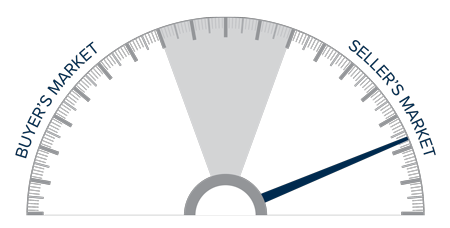
This speedometer reflects the state of the region’s real estate market using housing inventory, price gains, home sales, interest rates, and larger economic factors.

The numbers have yet to indicate that demand is waning amid rising interest rates, but this is sure to become a greater factor as we move into the spring. A leading indicator I pay attention to is changes to list prices and, in most counties, these continue to increase. This suggests that sellers remain confident they will be able to find a buyer even in the face of higher borrowing costs. If this pace of increase starts to soften, it may be an indication of an inflection point, but it does not appear to be that way yet.

Given all the factors discussed above, I have decided to leave the needle in the same position as the last quarter. The market still heavily favors sellers, but if rates rise much further, headwinds will likely increase.


As Chief Economist for Windermere Real Estate, Matthew Gardner is responsible for analyzing and interpreting economic data and its impact on the real estate market on both a local and national level. Matthew has over 30 years of professional experience both in the U.S. and U.K.

In addition to his day-to-day responsibilities, Matthew sits on the Washington State Governors Council of Economic Advisors; chairs the Board of Trustees at the Washington Center for Real Estate Research at the University of Washington; and is an Advisory Board Member at the Runstad Center for Real Estate Studies at the University of Washington where he also lectures in real estate economics.

This post originally appeared on the Windermere.com Blog.
Market Trends February 9, 2022

Q4 2021 Western Washington Real Estate Market Update

The following analysis of the Western Washington real estate market is provided by Windermere Real Estate Chief Economist Matthew Gardner. We hope that this information may assist you with making better-informed real estate decisions. For further information about the housing market in your area, please don’t hesitate to contact me.


REGIONAL ECONOMIC OVERVIEW

Just when we thought COVID was starting to pull back, the Omicron variant made its presence known. It is still too early to suggest that this has affected the region’s economic recovery—we won’t likely know for certain until we get more job data. I remain hopeful that this latest spike in infections will not have too much of an impact, but only time will tell. To date, the region has recovered all but 51,000 of the 297,000 jobs that were lost due to the pandemic. Some of the region’s smaller counties, including Grays Harbor, Cowlitz, Thurston, San Juan, and Clallam, have seen a full job recovery. The most recent data (November) shows the regional unemployment rate at a very respectable 3.3%, which is below the pre-pandemic low of 3.7%. The lowest unemployment rates were in King and San Juan Counties, where 2.9% of the labor force was out of work. The highest rate was in Grays Harbor County, which registered 5.1%. I still expect to see a full job recovery by this summer. However, there is a growing labor shortage holding the area back. Hopefully, this will change, but some industry sectors—especially hospitality—continue to find it hard to attract workers.

WESTERN WASHINGTON HOME SALES

❱ In the final quarter of the year, 22,161 homes sold, representing a drop of 5.2% compared to the same period in 2020 and down 18.8% from the third quarter.

❱ The reason there were lower year-over-year sales is simply because the number of homes for sale was down more than 30%. The drop between third and fourth quarters is likely due to seasonality changes in the market.

❱ Although home sales were lower in most markets, there was a significant uptick in Grays Harbor and Thurston counties. The number of homes sold dropped across the board compared to the third quarter.

❱ The ratio of pending sales (demand) to active listings (supply) showed sales outpacing listings by a factor of 5.2. The market is supply starved and unfortunately, it’s unlikely enough homes will be listed this spring to satisfy demand.

A bar graph showing the annual change in home sales for various counties in Western Washington during the fourth quarter of 2021.

WESTERN WASHINGTON HOME PRICES

A map showing the real estate market percentage changes in various counties in Western Washington during the fourth quarter of 2021.

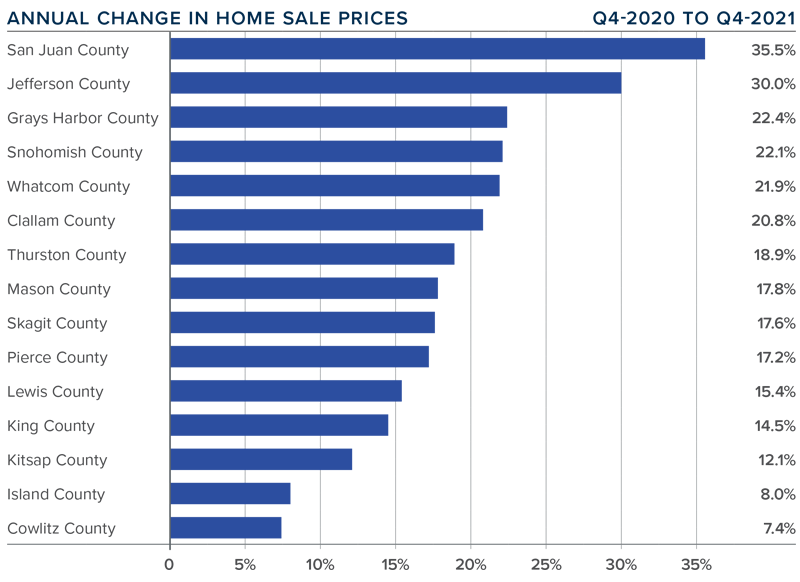
❱ Home prices rose 15.1% compared to a year ago, with an average sale price of $711,008. This was 2.1% lower than in the third quarter of 2021.

❱ When compared to the same period a year ago, price growth was strongest in San Juan and Jefferson counties. All but two markets saw prices rise more than 10% from a year ago.

❱ Relative to the third quarter, every county except Island (-8.6%), Mason (-5.2%), Lewis (-2.9%), King (-2.1%), Cowlitz (-1.7%), and Kitsap (-0.9%) saw sale prices rise.

❱ Mortgage rates rose more than .2% between the third and fourth quarters, which may have impacted prices. Affordability constraints continue to grow, which is also likely to have played a part in slowing gains.

A bar graph showing the annual change in home sale prices for various counties in Western Washington during the fourth quarter of 2021.

DAYS ON MARKET

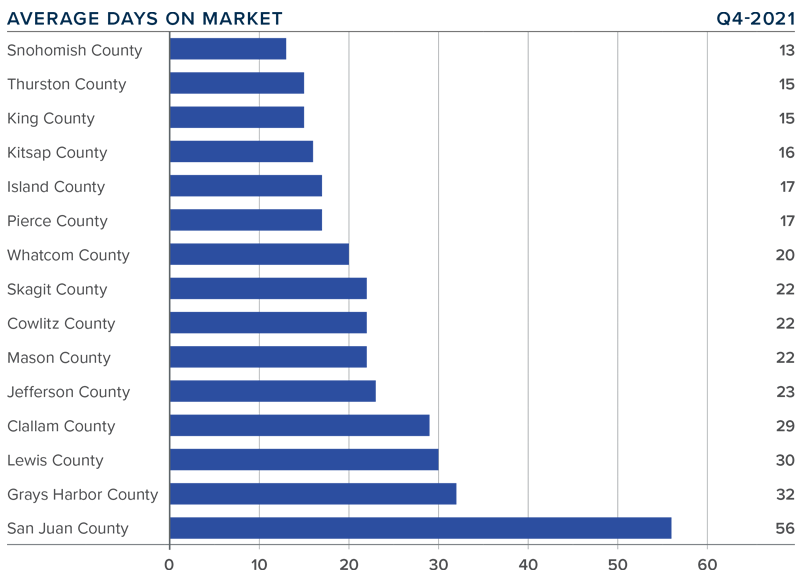
❱ It took an average of 23 days for homes to sell in the final quarter of 2021. This was 8 fewer days than in the same quarter of 2020, but 6 more days than in the third quarter of last year.

❱ Snohomish, Thurston, King, and Kitsap counties were the tightest markets in Western Washington, with homes taking an average of between 13 and 16 days to sell. The greatest drop in market time compared to a year ago was in San Juan County, where it took 33 fewer days for a seller to find a buyer.

❱ All counties contained in this report saw the average time on market drop from the same period a year ago. Every county except Whatcom saw market time rise compared to the third quarter.
❱ Longer days on market might suggest that things are starting to slow, but I don’t actually think this is the case. I believe buyers are being a little more selective before making offers, and many may be waiting in the hope that supply levels will improve in the spring.

A bar graph showing the average days on market for homes in various counties in Western Washington during the fourth quarter of 2021.

CONCLUSIONS

A speedometer graph indicating a seller's market in Western Washington during the fourth quarter of 2021.

This speedometer reflects the state of the region’s real estate market using housing inventory, price gains, home sales, interest rates, and larger economic factors.

The housing market remains in a state of imbalance, but, as I look at the data, I believe the frenetic pace of sales and price appreciation may start to soften in 2022.

This will likely be due to financing costs and affordability acting as headwinds to price growth. Mortgage rates have started to rise again, and I have forecasted them to reach 3.7% by fourth quarter. This alone will slow price growth as affordability in many areas declines.

One thing that remains unknown that could have a significant impact on the market is long-term work-from-home policies. Many businesses have not yet determined their plans for remote working, but once they do, potential home buyers who have been waiting to see how frequently they have to commute to work could immediately start their search. In addition to boosting sales, this could add inventory to the market as well.

All things considered, I am moving the needle just a notch toward buyers. However, as you can see, we are still in a market that heavily favors home sellers.

ABOUT MATTHEW GARDNER

Matthew Gardner - Chief Economist for Windermere Real Estate

As Chief Economist for Windermere Real Estate, Matthew Gardner is responsible for analyzing and interpreting economic data and its impact on the real estate market on both a local and national level. Matthew has over 30 years of professional experience both in the U.S. and U.K.

In addition to his day-to-day responsibilities, Matthew sits on the Washington State Governors Council of Economic Advisors; chairs the Board of Trustees at the Washington Center for Real Estate Research at the University of Washington; and is an Advisory Board Member at the Runstad Center for Real Estate Studies at the University of Washington where he also lectures in real estate economics.

For further information about the housing market or discuss real estate in your area, please don’t hesitate to contact me.

Market Trends November 17, 2021

11/15/2021 Housing and Economic Update from Matthew Gardner

BY: Matthew Gardner

This video is the latest in our Monday with Matthew series with Windermere Chief Economist Matthew Gardner. Each month, he analyzes the most up-to-date U.S. housing data to keep you well-informed about what’s going on in the real estate market. 

Hello there!  I’m Windermere Real Estate’s Chief Economist, Matthew Gardner, and welcome to the latest episode of Mondays with Matthew.

Before I get started, I wanted to let you know that this will be the final episode of Monday with Matthew for 2021 as I’m going to be taking Christmas off. So it’s time to offer you my forecasts for the U.S. economy and the country’s housing market in 2022.

Although many people – including myself – had hoped that COVID-19 would have become a somewhat distant memory by now, and that the economy would have recovered this was – sadly – not to be the case, and the pandemic’s influence on the economy is still being felt and all the datasets I track tell me that, although we are certainly healing, COVID continues to act as a drag on economic growth and I expect that to continue through the spring of next year – if not a little longer.

Economic Recovery & Growth

And it’s because of this that I – along with many other economists – have spent the last few months lowering our forecasts for economic growth – at least through the middle of 2022. So, let’s look at this a little closer.


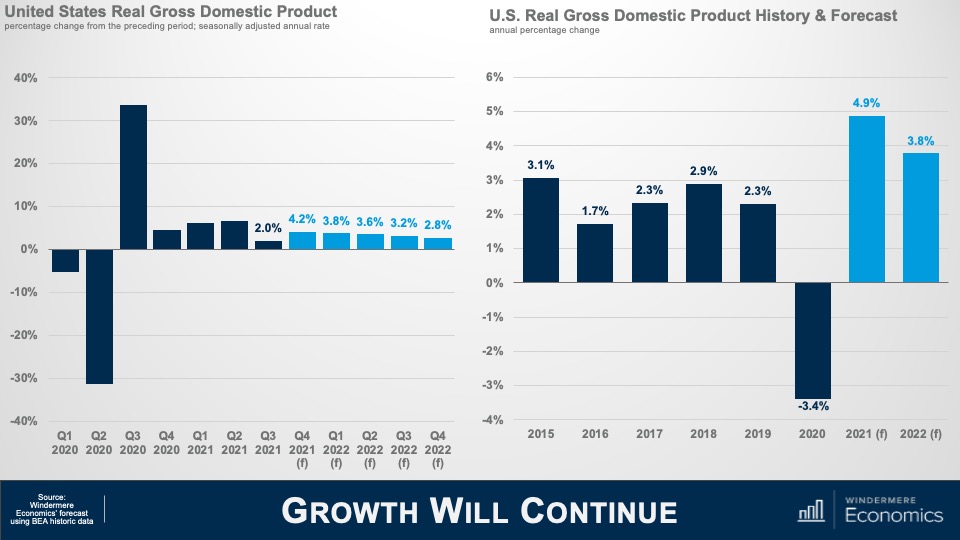
A slide of two bar graphs. The bar graph on the left is titled "United States Real Gross Domestic Product," showing Q1 2020 through Q4 2022 on the x-axis and negative 40 percent to 40 percent on the y-axis. The low GDP was in Q2 2020 around negative 30 percent and the high was Q3 2020 at over 30 percent. The second graph is title "U.S. Rea; Gross Domestic Product History & Forecast," showing the years 2015 through 2022 on the x-axis and negative 4 percent through 6 percent on the y-axis. The lowest annual percentage change was negative 3.4 percent in 2020 and the highest was 4.9 percent in 2021.


Here is my forecast for economic growth through the end of next year and you will note that, even though I am cautious in regard to the economy as we move through the winter and into 2022, I am still expecting to see a fairly decent bounce back in the fourth quarter of this year following the very disappointing rate that we saw in Q-3.

And on an annualized basis, I believe that the economy will have expanded by just shy of 5% this year and come in a little below 4% in 2022.

Simply put, the impacts of COVID-19 are going to continue to act as a drag on virus sensitive consumer services next year and ongoing supply chain issues will also delay inventory restocking. Both of these impacts have a depressing effect, in more ways than one, on economic growth, but I don’t see any chance that we will fall back into a recession.


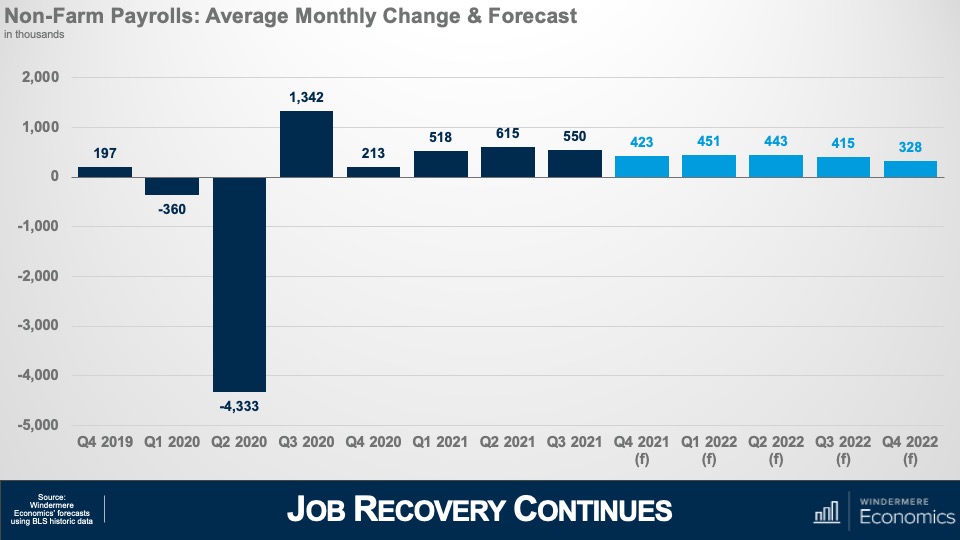
A bar graph titled "Non-Farm Payrolls: Average Monthly Change & Forecast," with Q4 2019 through Q4 2022 on the x-axis and figures in the thousands from negative 5,000 to 2,000 on the y-axis. The low was negative 4,333 on Q2 2020 and the high was 1,342 in Q3 2020.


Looking at the employment picture this chart shows my forecast for average monthly growth in jobs during a quarter and to give you some context, over the last decade or so the country has added an average of around 200,000 jobs per month during any one quarter and my forecast is for more robust employment growth as we move through 2022 and, if correct, I expect to see the country return to pre-COVID employment levels in the second half of the year.


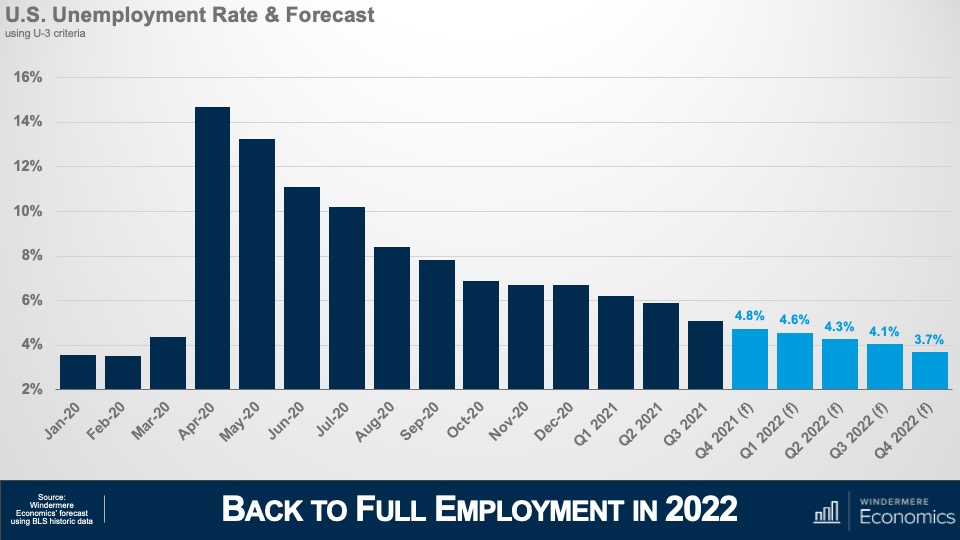
A bar graph titled "U.S. Unemployment Rate & Forecast," showing January 2020 to Q4 2022 on the x-axis and percentage figures on the y-axis, from 2% to 16%. The high was close to 15 percent in April 2020 and the low was just over 3 percent in January and February 2020.


And with jobs continuing to return I’m looking for the unemployment rate to continue trending lower and breaking south of 4% during the final quarter of the year. With the expiration of enhanced unemployment benefits – in concert with wages rising significantly in many face-to-face industries such as leisure and hospitality – prospects for people currently unemployed are looking rather good. That said, there are still millions of unemployed Americans who are not looking for work even with wages rising, the labor force still down by 3 million from its pre-pandemic peak, and this is worrying as businesses continue to have a hard time finding employees which raises the expectation that inflation will remain higher for longer than I would have liked to see.

Measures of Inflation

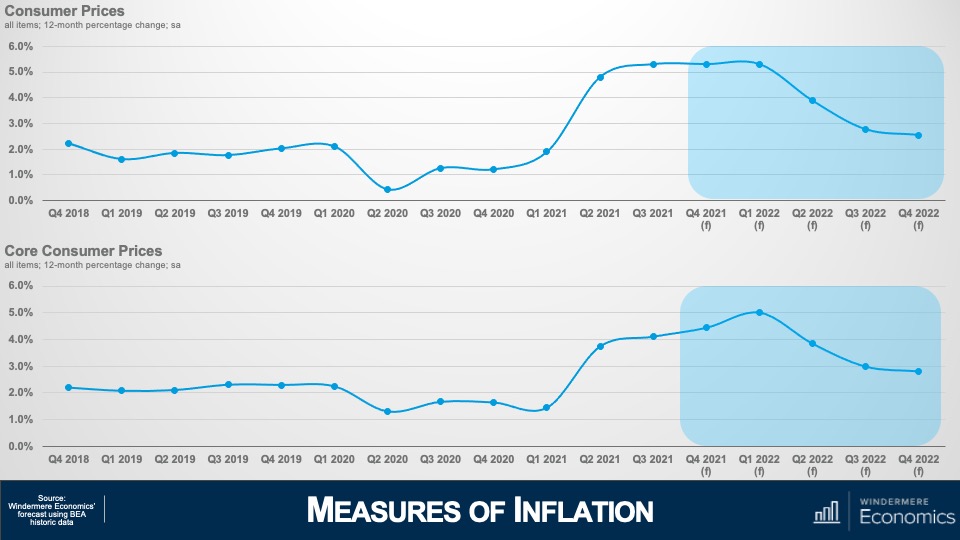
And that leads nicely into my final economic forecast and that is my outlook for inflation. As we have discussed, supply chain issues and labor shortages have increased prices significantly and this top chart shows annual changes in all consumer prices which I expect to remain around 5% until next spring, before gradually dropping down to below 3% by the end of the year.


A slide titled "Measures of Inflation" with two line graphs. One is titled "Consumer Prices" and shows the percentage changes on the y-axis and the quarters from Q4 2018 to Q4 2022 on the x-axis. It shows an expected drop from Q4 2021 to Q4 2022. The "Core Consumer Prices" graphs showing the same measurements on each axis. It shows an expected increase in core consumer prices in Q1 2022 followed by an expected drop toward Q4 2022.


But the core inflation rate – which excludes the volatile food and energy sectors – won’t peak until early next year before it too starts to gradually pull back and, at these levels, the Federal Reserve will undoubtedly have started to raise interest rates to counteract inflationary pressures. This is not pretty, but I absolutely do not believe that we are in some sort of inflationary spiral, or that “stagflation” will raise its ugly head again.

U.S. Housing Market

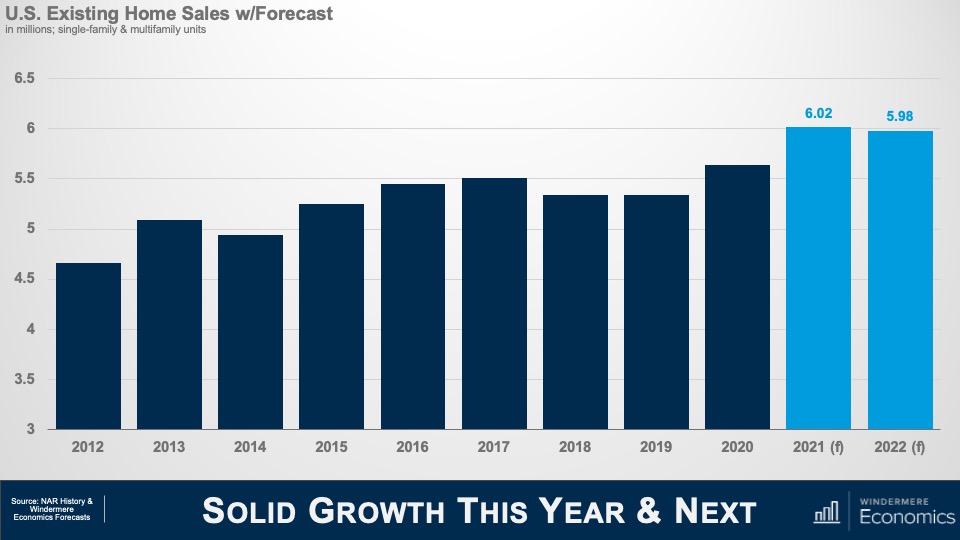
Okay! Now it’s time to turn our attention to the U.S. housing market which was a beacon of hope during the pandemic period and, given the massive spike in demand that started last June, I’m looking for a little more than 6 million existing homes will have changed hands in 2021, but I don’t see this level increasing in 2022 – mainly due to ongoing supply limitations as well as rising affordability issues, and I’m therefore forecasting sales to pull back  – albeit very modestly – next year. That said, the country has never seen more than 6 million home selling in a single year since records were first kept so the number is still very impressive.


A slide titled "Solid Growth This Year & Next" with a bar graph titled "U.S. Existing Home Sales w/ Forecast." It shows the existing home sales in millions every year from 2021 to 2022. 2021 and 2022 have the highest figures on the graph, at 6.02 and 5.98 million respectively.


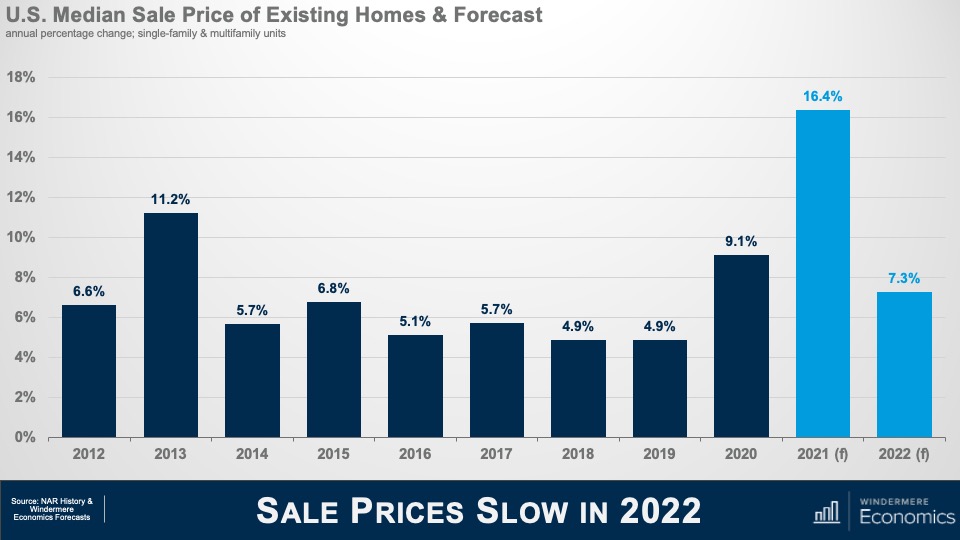
And with the market as tight as it has been so far this year, it shouldn’t be any surprise to see median sale prices skyrocketing and, even though we have 3 more months of sales data yet to be released, I still anticipate prices will have risen by almost 16 and a half % in 2021- a quite remarkable number. This pace of appreciation has never been seen before. In fact, the closest was back in 2005 – when the housing bubble was inflating rapidly – but even then, prices only rose by 12.2%.


A slide titled " Sales Prices Slow in 2022," with a bar graph titled "U.S. Median Sale Price of Existing Homes & Forecast," which shows the annual percentage change of single-family and multifamily units for the years 2012 through 2022. The highest figure is 16.4 percent in 2021, whereas the lowest in both in 2018 and 2019 at 4.9 percent.


But, as I mentioned in my sales forecast, this pace of growth is unsustainable and I am expecting to see some of the heat to come off the market next year but, a growth rate of 7.3% is certainly nothing to sniff at.

There are three major reasons why we will see the pace of growth slow. I have already mentioned my concerns regarding housing affordability, but mortgage rates and new supply will both influence the slowdown in sales and price growth in the resale arena.


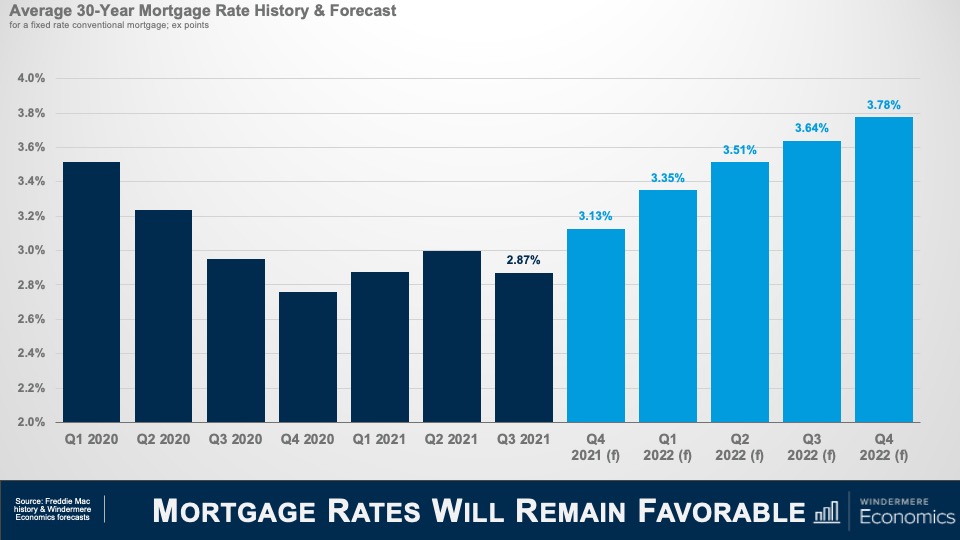
A slide titled "Mortgage Rates Will Remain Favorable" with a bar graph titled "Average 30-Year Mortgage Rate History & Forecast." It shows a predicted increase mortgage rates from Q4 2021 at 3.13 percent to 3.78 percent in Q4 2022.


Although I do not prepare a forecast for housing affordability, this is my where I expect to see mortgage rates through the end of next year and I am looking for them to continue “stair-stepping” higher but still ending 2022 below 4% – very low by historic standards given that the long-term average for a conventional 30-year mortgage is somewhere around 7 1/2%.

Obviously, as rates notch higher that starts to compress price growth as it puts a lower ceiling on how much a buyer can afford to pay for a home.


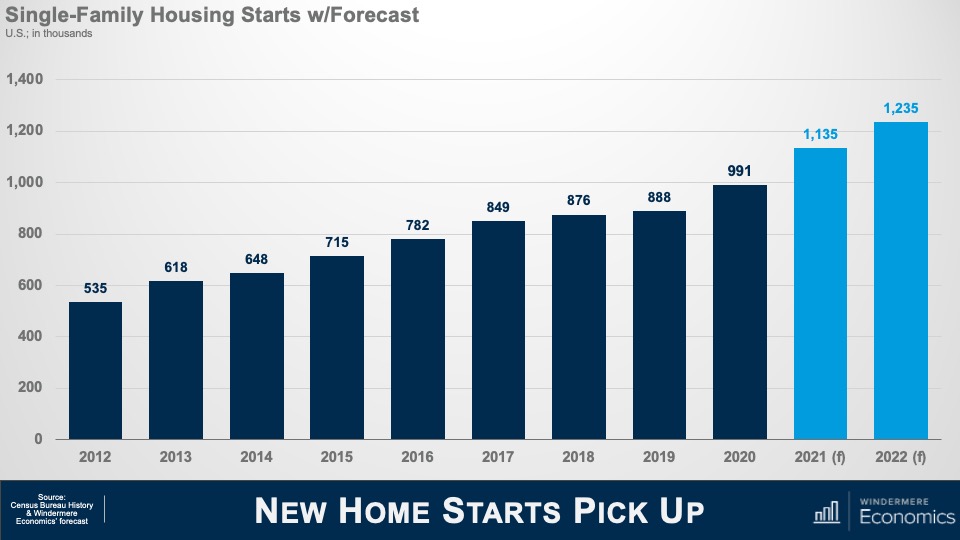
A slide titled "New Home Starts Pick Up," with a bar graph titled "Single-Family Housing Starts w/ Forecast." The graph shows the housing starts in the thousands for the years 2012 through 2022. There is a gradual increase, from 535,000 in 2012 to an expected figure of over 1.2 million in 2022.


And slowing growth in existing home prices and sales will also be a function of additional supply and this chart shows my forecast for single-family starts this year and next. I expect more than a million homes to start construction in 2022 – continuing the trend that started in mid-2020 – but I am sure that some of you may be asking yourselves that if starts are already robust, how have existing home sales been able to increase so significantly if there has been solid supply coming from homebuilders – and that would be a great question.

And I would answer this by telling you that the way the Census gathers data on start is to count the number of home foundations that have been poured, but vertical construction has not necessarily started. And what we have been seeing is a lot of foundations but not so many homes actually being built – and we know this by looking at the number of homes that are for sale but have yet to be started. So, it’s important to look at a separate number that the Census Bureau also puts out which counts the number of units actually under construction, and that number has been growing significantly over the course of the last 18 months or so.


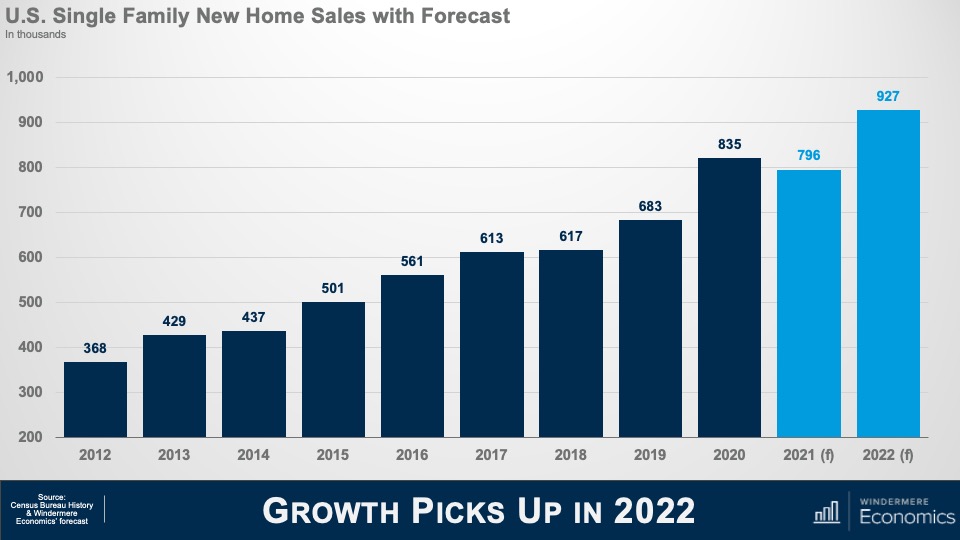
A slide titled "Growth Picks Up in 2022," with a bar graph titled "U.S. Single Family New Home Sales with Forecast." The graph shows the new home sales in thousands for the years 2012 through 2022. Sales were at a low of 368,000 in 2012, jumped to 835,000 in 2020, and are predicted to peak at 927,000 in 2022.


Builders have been hamstrung with rising labor and material costs which will lead new home sales this year to fall below the number seen in 2020; however, I do expect this to pick up significantly next year and my current forecast calls for 927,000 new homes to be sold in 2022.

So, there you have it, my economic and housing market forecast for 2022.

Of course, there are still a number of variables that could lead me to revise this forecast but, as an old economics professor of mine used to tell me, “Gardner, forecast well, but forecast often!”

If everything goes according to my plan, you should expect to see the housing market start to move towards some sort of balance next year, but I am afraid that it will still remain out of equilibrium until at least 2023.

And if you’re wondering, no, I don’t see a housing bubble forming and I’m also not at all concerned about homeowners currently in forbearance, but it would be silly to say that there aren’t any issues in the housing market that concern me because there are and the biggest of which is housing affordability and this will have a significant impact on the millennial generation who are continuing to get older, and they are all – well most – thinking about settling down and, possibly, having children, and I wonder how hard it will be for many of them to be able to afford to buy their first home because most really do want to become homeowners. Will builders figure out how to build to this massive pent-up demand? I guarantee you that whoever can solve this puzzle will do very, very well.

COVID-19 caused an unparalleled shock to the US economy and the rise of the delta variant has certainly impacted the speed of our recovery but, rest assured, this particular forecaster firmly believes that we will recover and that the economy will continue to grow.

Demand for ownership housing remains remarkably buoyant and, in fact, it is quite likely that demand may actually increase with the work from home paradigm that will start to gain momentum next year. It will be fascinating to watch how this impacts not just demand, but where these buyers will ultimately choose to live.

In closing, I very much hope that you have all enjoyed the videos that I have shared this year as much as I have enjoyed making them.

As always if you have any questions or comments about this topic, please do reach out to me but, in the meantime, stay safe out there and I look forward the visiting with you all again next year.

Bye now.